Coastal vs Inland Mortgage Lead Strategies for Regional Lenders
Regional mortgage lead strategies for coastal versus inland markets help lenders allocate budget and tailor product focus. Call (510)-663-7016 to get started.
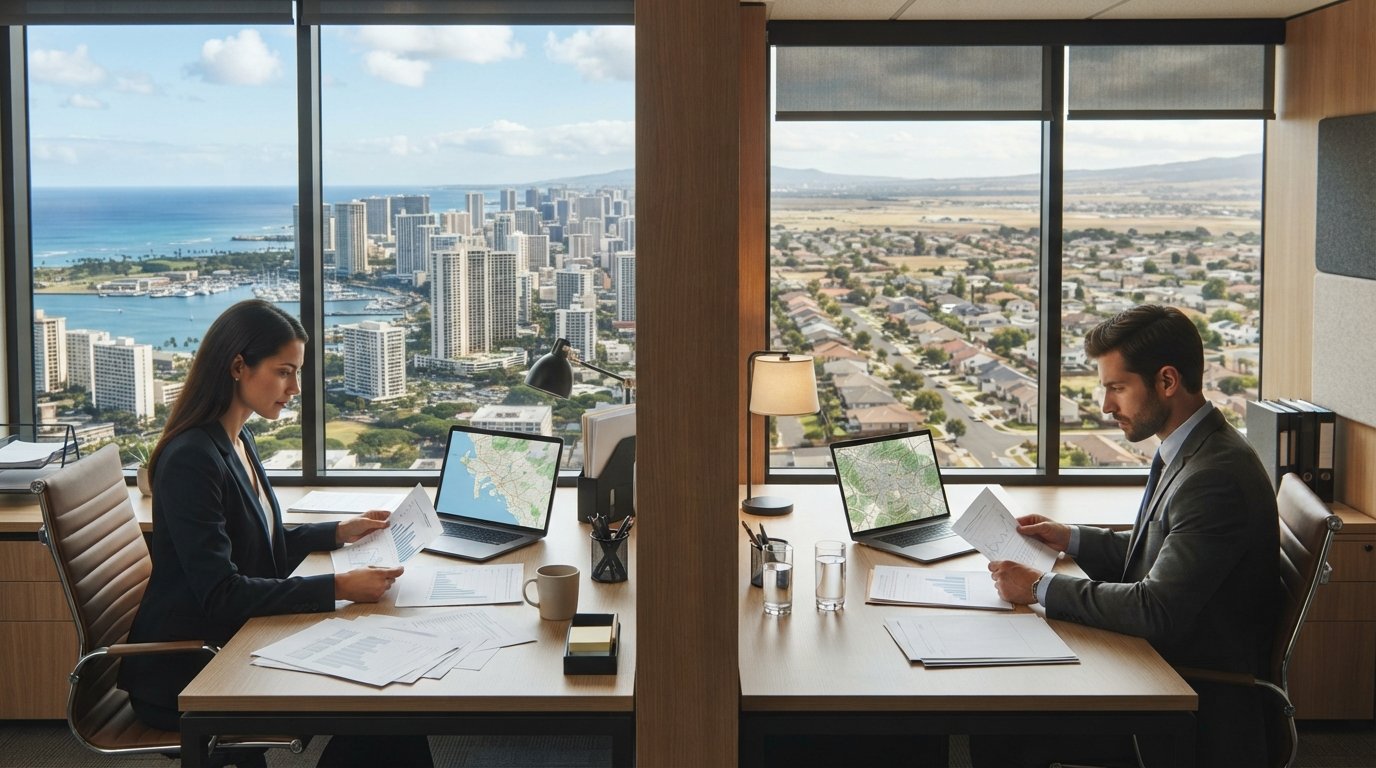
Mortgage professionals who operate across multiple regions know that a single lead strategy rarely works everywhere. The housing market in a coastal metro like Seattle or Boston behaves very differently from an inland market like Denver or Buffalo. Price appreciation, inventory levels, equity positions, and even consumer motivation shift dramatically from one region to the next. That means your approach to buying, filtering, and converting mortgage leads must adapt to local conditions. This article breaks down regional mortgage lead strategies for coastal versus inland markets, giving you a practical framework to allocate budget, choose product focus, and tailor messaging so you can win more loans in every territory you serve.
Why Regional Differences Matter in Mortgage Lead Generation
Coastal and inland markets diverge on nearly every metric that drives mortgage demand. Coastal areas typically feature high home prices, limited inventory, and strong equity gains over the past decade. Inland markets often have more affordable housing stock, faster population growth, and higher concentrations of first-time buyers. These structural differences change what consumers need and how they respond to outreach.
For lenders buying leads, this means a coastal lead might be a homeowner sitting on substantial equity who is considering a cash-out refinance or a HELOC. An inland lead might be a renter looking to purchase their first home or a homeowner seeking a rate-and-term refinance after a recent rate drop. Understanding these patterns helps you filter and target the right products in the right places.
MortgageLeads.com allows you to filter leads by geographic and demographic criteria, which is essential when you are managing campaigns across diverse markets. You can select specific states, metros, or even ZIP codes, and pair those filters with product-specific lead types such as refinance, home equity, new purchase, or reverse mortgage. That level of granularity is the foundation of any regional strategy.
Coastal Market Dynamics: High Prices, Low Inventory, Strong Equity
Coastal markets are characterized by expensive housing, constrained supply, and homeowners who have accumulated significant equity. In cities like San Francisco, New York, or Boston, median home values often exceed inland markets by a factor of two or more. Inventory remains tight because of zoning restrictions, geographic limits, and strong demand. As a result, purchase transactions are competitive, and many buyers are well-qualified but face limited options.
For mortgage lead strategies, this environment creates distinct opportunities. Homeowners in coastal markets are prime candidates for home equity products, including HELOCs and cash-out refinances. Even a small percentage gain in home value translates into a large dollar amount of tappable equity. At the same time, high prices mean that purchase leads are valuable but may require more nurturing because buyers are often waiting for the right property to appear.
Refinance activity in coastal markets tends to be driven by rate movements and debt consolidation rather than by home price appreciation alone. Borrowers with large balances are sensitive to rate changes, and even a modest rate reduction can produce meaningful monthly savings. However, because loan amounts are higher, lenders must ensure they have the capacity and appetite for jumbo or high-balance conforming loans.
When buying leads in coastal markets, consider these priorities:
- Emphasize home equity and cash-out refinance leads, as equity-rich homeowners are more likely to transact.
- Filter for higher loan amounts or specific property types to match your lending capacity.
- Expect longer purchase cycles and invest in follow-up, because inventory constraints can delay closings.
- Use live transfers for equity products, since homeowners often have questions that require immediate conversation.
These priorities reflect the reality that coastal borrowers often need education about how to access their equity efficiently. A live transfer that connects a homeowner with a loan officer within seconds can dramatically improve conversion, especially when the homeowner is already exploring options online.
Inland Market Dynamics: Affordability, Growth, and First-Time Buyers
Inland markets tell a different story. Cities like Denver, Austin, Boise, and Buffalo have seen strong population growth, but home prices remain more affordable relative to local incomes. Inventory is generally less constrained, and new construction plays a larger role in meeting demand. Many inland markets also have a higher share of first-time buyers and younger households entering homeownership.
In this environment, purchase leads are often the highest-value segment. First-time buyers are actively searching, and they need guidance on down payment assistance, FHA loans, and closing cost options. Refinance demand exists but tends to be more rate-sensitive and less driven by equity extraction. Home equity products are still relevant, but the average equity position is lower than in coastal markets, so the pool of qualified homeowners is smaller.
Lead strategies for inland markets should prioritize volume and speed-to-contact. Because purchase transactions often move quickly and buyers may be less experienced, the first lender to respond has a significant advantage. Using real-time leads and live transfers can help you engage buyers while they are still actively shopping. Additionally, filtering for FHA-eligible or first-time buyer segments can improve efficiency.
Consider these inland market priorities:
- Focus on new purchase and first-time buyer leads, especially in growth corridors and suburbs.
- Use FHA and conventional purchase filters to align with local income and credit profiles.
- Maintain a fast follow-up cadence, because inland buyers often contact multiple lenders.
- Test shared leads for volume and exclusive leads for higher-touch conversion.
Inland markets also benefit from localized messaging that speaks to affordability, community growth, and down payment assistance programs. A generic coastal-focused message about equity tapping will fall flat with a first-time buyer in a suburb of Denver. Tailoring your script and email content to the local market is essential.
Adjusting Product Focus by Region
One of the most effective ways to improve ROI is to shift product emphasis based on regional conditions. In coastal markets, home equity and refinance products often deserve a larger share of your lead budget. In inland markets, purchase and first-time buyer products should dominate. This does not mean you ignore other products entirely, but rather that you allocate resources where demand is strongest.
For example, a lender operating in both Seattle and Spokane might buy home equity leads heavily in Seattle while focusing on new purchase leads in Spokane. The same lender could use reverse mortgage leads in coastal retirement communities where home values are high and older homeowners have significant equity. In inland markets, reverse mortgage demand may be lower or concentrated in specific neighborhoods.
MortgageLeads.com offers a range of lead types that map well to these regional strategies. You can purchase refinance leads, new purchase leads, home equity leads, and reverse mortgage leads, each with filtering options. By monitoring performance data, you can quickly see which products convert best in each market and adjust your buying accordingly.
Budget Allocation Across Markets Using Lead Performance Data
Allocating budget across regions is both an art and a science. The key is to let performance data guide your decisions rather than relying on assumptions. Start by defining clear KPIs for each market: cost per lead, contact rate, conversion rate to application, and funded loan rate. Then compare those metrics across coastal and inland territories to identify where your dollars work hardest.
A practical approach is to run small tests in each market before scaling. For instance, you might buy a batch of exclusive leads in a coastal metro and a comparable batch in an inland metro, then track results for 30 to 60 days. This gives you a baseline for cost per funded loan. Once you have that data, you can shift budget toward the markets and products that produce the lowest cost per acquisition.
Keep in mind that lead prices vary by product and region. MortgageLeads.com provides representative pricing, but actual packages and prices can change, so always check current offerings on the product pages. As a general guide, live transfers for refinance and purchase tend to be premium products, while shared leads and home equity leads may be more affordable. Use these price differences to build a blended strategy that balances volume and efficiency.
Another useful tactic is to set lead buying caps by market. If a coastal market is saturated or your team lacks capacity, cap spending there and reallocate to inland markets with higher growth potential. Conversely, if a coastal market is performing well, you can increase caps gradually while monitoring contact and conversion rates.
Localized Messaging and Licensing Considerations
Messaging must resonate with local conditions. Coastal homeowners may respond to language about unlocking equity, renovating to increase value, or consolidating higher balances. Inland buyers may respond better to messages about affordability, down payment help, and building wealth through homeownership. Your scripts, emails, and landing pages should reflect these differences.
Licensing is another critical factor. Mortgage lending is regulated at the state level, and your team must be properly licensed in each state where you buy leads. Some states have specific disclosure requirements or restrictions on lead generation and telemarketing. Before expanding into a new region, confirm that your licensing covers the products you plan to offer and that your lead sources comply with state regulations.
Working with a lead provider that understands these nuances can reduce risk. MortgageLeads.com sources consumer inquiries through digital channels and verifies them for mortgage-specific intent before distribution. This verification helps ensure that the leads you receive are genuinely interested in mortgage products, which is especially important when you are marketing across state lines.
For lenders who also want to diversify their lead sources, exploring complementary verticals can be smart. For example, BestInsuranceLeads connects insurance agents with verified consumer leads, and the same disciplined approach to regional targeting applies. However, for mortgage-specific needs, sticking with a specialized platform like MortgageLeads.com ensures your filters and lead types align with lending requirements.
Building a Regional Lead Strategy That Scales
To operationalize a coastal versus inland strategy, start by mapping your target markets and identifying the dominant product demand in each. Then build separate lead buying campaigns for each region, with distinct filters, budgets, and messaging. Use the platform's geographic and demographic filters to target specific counties or metros, and monitor performance weekly.
If you are also focused on first-time buyers, our guide on how to generate first-time home buyer mortgage leads provides additional tactics that pair well with inland market strategies. Combining regional targeting with product-specific playbooks can significantly improve your conversion rates.
Finally, remember that lead strategies are not static. Housing markets shift, rates change, and inventory levels fluctuate. Schedule quarterly reviews of your regional performance and be prepared to reallocate budget as conditions evolve. By staying data-driven and regionally aware, you can build a mortgage lead strategy that performs across both coastal and inland markets.
For questions about lead availability, filters, or integration options, contact MortgageLeads.com directly or call (510)-663-7016 to speak with a representative. With the right regional approach, you can turn geographic diversity into a competitive advantage.