First Time Home Buyer Lead Conversion Strategies That Work
Master first time home buyer lead conversion strategies to turn inquiries into closed loans. Call 5106637016 for expert guidance.
By Lyra Ashbourne
First time home buyers represent one of the most rewarding yet challenging segments in mortgage lending. They are eager, motivated, and often overwhelmed by the complexity of the homebuying process. For loan officers and mortgage brokers, capturing their attention is only half the battle. The real challenge lies in converting those leads into funded loans. With competition intensifying across digital channels, having a refined approach to first time home buyer lead conversion strategies can mean the difference between a pipeline full of dead ends and a steady stream of closed deals.
The stakes are high because first time buyers often lack the knowledge to navigate the process alone. They need guidance, reassurance, and timely communication. When you deliver those elements effectively, you build trust that translates into loyalty and referrals. This article explores proven methods to move first time buyers from initial inquiry to closing table, with actionable steps you can implement immediately.
Understanding the First Time Home Buyer Mindset
Before diving into tactics, it helps to understand who you are dealing with. First time home buyers are not just purchasing a house; they are stepping into unfamiliar territory. Many are millennials or Gen Z consumers who have done extensive online research before ever contacting a lender. They arrive with questions, anxieties, and a healthy dose of skepticism. They have likely read reviews, compared rates, and maybe even spoken with a competitor already.
This means your initial response must demonstrate expertise and empathy in equal measure. A generic email or a delayed phone call will send them straight to the next lender on their list. According to industry data, the average response time for mortgage leads is often measured in hours, but top performers respond within minutes. Speed signals seriousness. When you combine rapid response with personalized messaging, you immediately differentiate yourself from the pack.
Additionally, first time buyers often face specific financial hurdles: student loan debt, limited savings for down payments, and uncertainty about credit score requirements. Your ability to address these concerns head-on, without judgment, positions you as a trusted advisor rather than a salesperson. This foundational trust is the bedrock of any successful conversion strategy.
Lead Qualification: Separating Serious Buyers from Browsers
Not every lead is ready to buy today. Some are in the early research phase, while others are pre-approved and actively house hunting. The key is to qualify quickly so you can allocate your time where it matters most. Effective qualification goes beyond checking a credit score. It involves understanding timeline, motivation, and financial readiness.
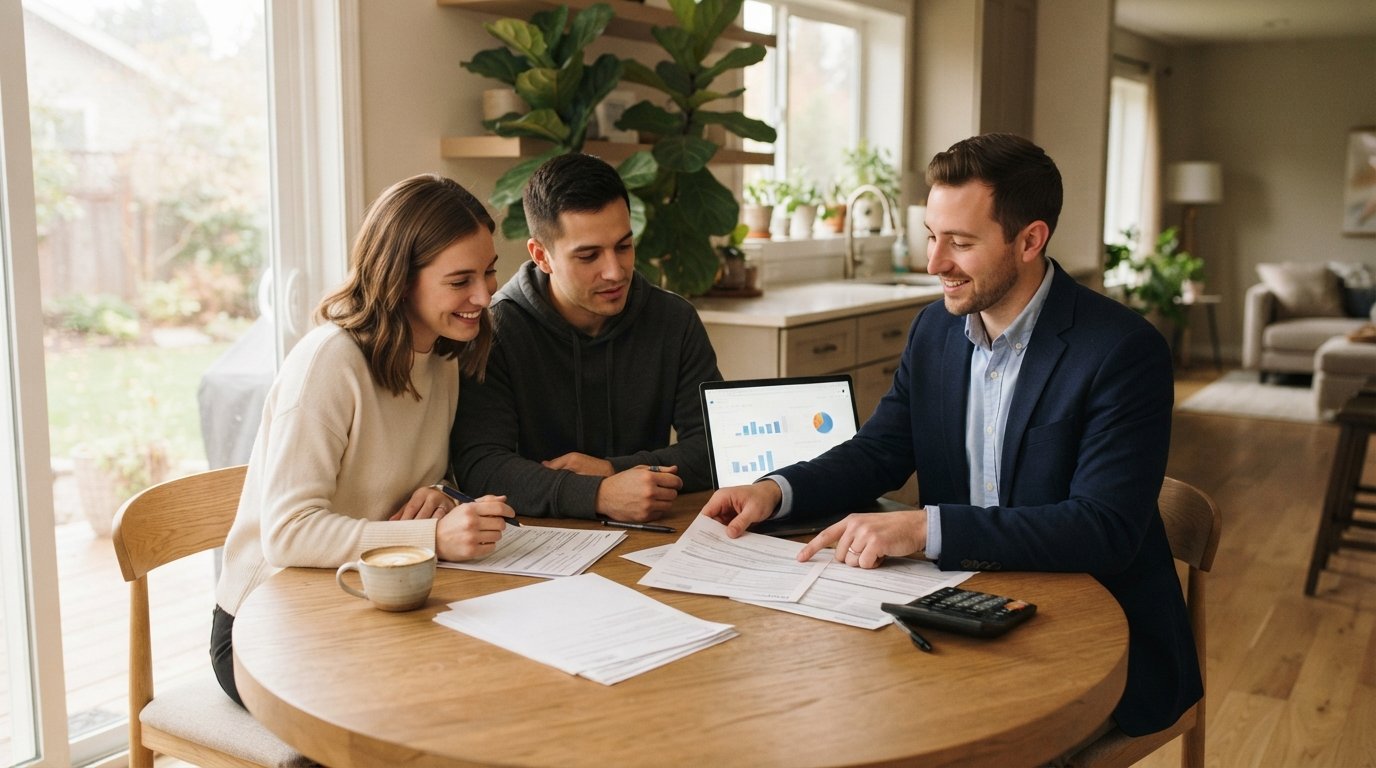
Start with a structured qualification framework. Ask open-ended questions that reveal intent: When are you hoping to move? Have you spoken with a real estate agent yet? What is your ideal monthly payment? These questions not only gather information but also show that you are invested in their specific situation.
Consider using a lead scoring system to prioritize follow-up. Leads that provide detailed information and engage with your initial outreach should be moved to the top of your list. Those who are unresponsive after multiple attempts may need to be placed in a long-term nurture campaign. This prevents you from wasting energy on prospects who are months away from making a decision.
- Timeline: Are they looking to buy within 30 days, 90 days, or just exploring?
- Financing status: Have they been pre-approved by another lender?
- Engagement level: Did they open your email, click a link, or reply to a text?
- Property type: Are they interested in a single-family home, condo, or multi-family?
- Down payment readiness: Do they have funds available, or are they relying on assistance programs?
Once you have this information, you can tailor your communication to match their stage in the journey. A buyer who is 90 days out does not need the same urgency as one who is ready to make an offer next week. By segmenting your leads, you deliver the right message at the right time.
Speed to Lead: The Make-or-Break Factor
In mortgage lead conversion, speed is not just a nice-to-have; it is a competitive advantage. Research consistently shows that contacting a lead within the first five minutes dramatically increases the likelihood of connection. After an hour, the odds plummet. For first time buyers who are often comparing multiple lenders simultaneously, being the first to respond can seal the deal.
To achieve this level of responsiveness, you need systems in place. Live transfer leads, for example, connect you directly with a consumer who is actively seeking a mortgage. These are among the highest-converting lead types because there is no delay. Platforms like MortgageLeads.com offer live transfers with a 90-second buffer, ensuring you have context before the call connects. This immediacy builds instant credibility.
If you are working with online form leads, set up automated alerts and have a dedicated team member ready to call within minutes. Even a quick text message acknowledging their inquiry can buy you time until you can speak by phone. The goal is to establish contact before your competitors do.
It is also worth tracking your conversion rates by geographic area. In our guide on track lead conversion by city, we explain how location-specific data can reveal which markets respond best to your outreach. This insight allows you to refine your targeting and allocate resources more efficiently.
Building Trust Through Education and Communication
First time buyers are hungry for information. They want to understand the difference between FHA and conventional loans, how closing costs work, and what mortgage insurance entails. If you can be their primary source of clear, jargon-free education, you become their go-to advisor. This educational approach is not just altruistic; it is a powerful conversion tool.
Consider creating a series of automated emails that walk buyers through the mortgage process step by step. Each email should address a common question or concern, such as "How to Improve Your Credit Score Before Applying" or "Understanding Down Payment Assistance Programs." By providing value upfront, you keep your brand top of mind and reduce the anxiety that often causes buyers to stall.
Phone calls should complement these emails. A personal check-in to see if they have questions about the information you sent demonstrates that you are paying attention. During these calls, listen more than you talk. Let them voice their concerns, and then offer solutions. This consultative approach builds rapport and positions you as a partner in their journey.
Remember that first time buyers often rely on referrals from friends and family. When you treat them well, they are likely to share their experience with others. That organic word-of-mouth can become a significant source of future leads.
Leveraging Technology for Nurturing Leads
Technology can streamline your follow-up and ensure no lead falls through the cracks. A robust Customer Relationship Management (CRM) system is essential. It should allow you to track interactions, set reminders, and automate personalized communication. Many CRMs integrate directly with lead providers, so leads flow seamlessly into your pipeline.
MortgageLeads.com, for instance, supports API integration with third-party quoting engines and CRMs. This means you can receive leads in real time and immediately trigger a welcome sequence. The platform also offers various lead types, including exclusive, shared, and live transfers, so you can choose the format that aligns with your capacity and budget.
Beyond CRM, consider using SMS messaging for quick updates. Text messages have high open rates and are less intrusive than phone calls for initial contact. Just be sure to comply with all regulations, including obtaining proper consent. When used correctly, text can be a powerful tool for scheduling appointments and answering simple questions.
If you are looking to expand your reach beyond mortgage leads, partnering with a trusted data broker can help. For example, BestInsuranceLeads connects insurance agents with high-intent consumer leads, which can be a complementary offering if you also provide home and auto insurance referrals. Cross-selling opportunities like these can increase your overall revenue per client.
Overcoming Common Objections
Even with the best nurturing, first time buyers will raise objections. Common concerns include fear of being locked into a bad rate, uncertainty about affording a down payment, and anxiety about the long-term commitment of a mortgage. How you handle these objections can determine whether the lead converts or walks away.
Preparation is key. Anticipate the most frequent objections and craft responses that are both reassuring and factual. For instance, if a buyer says they cannot afford a 20 percent down payment, explain the benefits of FHA loans with as little as 3.5 percent down. If they worry about closing costs, discuss seller concessions and lender credits.
Role-playing with your team can help refine these responses. Practice turning objections into opportunities to educate. When a buyer sees that you have a solution for their problem, their confidence in you grows. This confidence is what ultimately leads to a signed application.
Strategies for Re-Engaging Dormant Leads
Not every lead will convert immediately. Some will go cold, only to resurface months later when their situation changes. A robust re-engagement strategy ensures you are there when they are ready. Dormant leads are not dead leads; they are simply not ready yet.
Set up a long-term nurture campaign that includes periodic check-ins, market updates, and relevant educational content. For example, if mortgage rates drop, send a quick note letting them know it might be a good time to revisit their pre-approval. If they mentioned a specific concern, such as saving for a down payment, share information about down payment assistance programs that have become available.
Another effective tactic is to offer a free homebuyer seminar or webinar. This positions you as a community resource and gives leads a low-pressure way to re-engage. Even if they do not attend, the invitation keeps your name in front of them.
Tracking the performance of these re-engagement efforts is crucial. Use your CRM to monitor open rates, click-throughs, and responses. Over time, you will identify which messages resonate and which fall flat, allowing you to continuously improve your approach.
Measuring Success and Iterating
Conversion strategies are not set in stone. What works today may not work tomorrow, especially as market conditions shift. To stay ahead, you must measure your results and iterate based on data. Key metrics to track include lead response time, contact rate, appointment set rate, and closed loan rate.
Break down these metrics by lead source. Are live transfers converting better than online form leads? Are exclusive leads outperforming shared leads? Understanding the nuances helps you allocate your budget more effectively. If a particular source is underperforming, either adjust your approach or reallocate resources to higher-yielding channels.
Also, solicit feedback from your clients. Ask them what made them choose you over other lenders. Their answers can reveal strengths you did not know you had and areas for improvement. Continuous refinement is the hallmark of a successful lead conversion strategy.
In conclusion, converting first time home buyer leads requires a blend of speed, empathy, education, and technology. By understanding their mindset, qualifying efficiently, and nurturing with value, you can turn inquiries into lifelong clients. The strategies outlined here provide a roadmap, but the execution is up to you. Stay responsive, stay informed, and always put the buyer's needs first. That is the surest path to sustainable success in mortgage lending.