First Time Home Buyer Leads: Convert Hesitant Borrowers
Convert hesitant first time home buyer leads with trust-building follow-up. Call (510)-663-7016 to discuss strategies that turn caution into applications.
By Vivienne Solace
Hesitant borrowers are not lost borrowers. They are borrowers who have not yet found a reason to trust the process, the numbers, or you. For mortgage professionals working first time home buyer leads, that distinction matters more than any script or dialing cadence. First time buyers carry a unique mix of excitement and fear: excitement about owning a home, fear about credit damage, hidden costs, and making a decision they cannot undo. Convert that hesitation into confidence and your pipeline fills itself.
This guide breaks down why first time buyers stall, how to diagnose the specific source of hesitation on each call, and which follow-up frameworks move a cautious prospect toward a pre-approval application. Whether you buy new purchase leads, run pay-per-call campaigns, or work live transfers, the principles below apply. The goal is not to pressure anyone. The goal is to remove the friction that keeps a ready buyer sitting on the fence.
Why First Time Home Buyers Hesitate
Before you can convert hesitation, you need to name it. Most first time buyers fall into one of a few hesitation profiles, and each one requires a different response. A borrower who worries about credit score damage needs education about soft pulls and pre-qualification. A borrower who worries about affordability needs a clear monthly payment range with taxes and insurance included. A borrower who worries about commitment needs to understand contingencies, inspection periods, and the difference between pre-approval and a binding contract.
The mistake many loan officers make is treating all hesitation as the same objection. When a lead says "I am not ready yet," that phrase can mean six different things. It can mean the down payment is not saved. It can mean a partner or family member has not agreed. It can mean they were burned by a previous lender. It can mean they simply do not understand how much house they can afford. If you respond to all of these with the same rate quote, you will lose most of them.
There is also a structural reason first time buyers hesitate in 2026: information overload. A prospect can visit twenty websites in an evening and receive conflicting answers about credit requirements, assistance programs, and closing costs. That confusion does not produce action. It produces paralysis. Your job as the professional on the other end of the phone is to replace noise with a simple, accurate next step.
Qualify First Time Home Buyer Leads for Real Intent
Conversion starts before the first conversation. Lead quality determines how much of your time goes toward real opportunities versus dead ends. When you source first-time home buyer mortgage leads, look for signals that separate genuine buyers from casual browsers: a stated timeline, a price range, a down payment status, and a reason for buying now. These four data points predict conversion far better than any demographic filter alone.
Real-time delivery matters as much as data quality. A first time buyer who fills out a form at 9 p.m. and hears from a loan officer at 9:04 p.m. is a very different prospect than one who hears back two days later. Response speed is one of the strongest conversion levers in mortgage lead generation, and it is one of the easiest to control. If your current lead source batches leads overnight, you are handing your competitors the first conversation.
Consider how delivery format changes your approach. Exclusive leads let you control the entire narrative and follow-up sequence. Shared leads require faster contact and sharper differentiation. Live transfers put you on the phone with a consumer who is already engaged, which shortens the trust-building phase considerably. Pay-per-call models, such as those described by PayPerCallMarketing, connect advertisers with publishers who generate qualified inbound calls, which means the prospect has already raised a hand and asked to speak with someone.
No matter which format you choose, verify intent before you invest hours. A short qualification framework keeps your pipeline honest:
- Timeline: Are they hoping to buy within 30 days, 90 days, or simply exploring?
- Financing status: Do they know their credit range and savings position?
- Property type and location: Do they have a specific area or home style in mind?
- Decision makers: Is a spouse, partner, or family member part of the decision?
- Motivation: What is pushing them to buy now instead of next year?
Those five answers tell you whether you are working a lead or babysitting a maybe. They also give you the raw material for personalized follow-up, which is where most hesitant borrowers are actually won.
Build Trust Fast with First Time Buyers
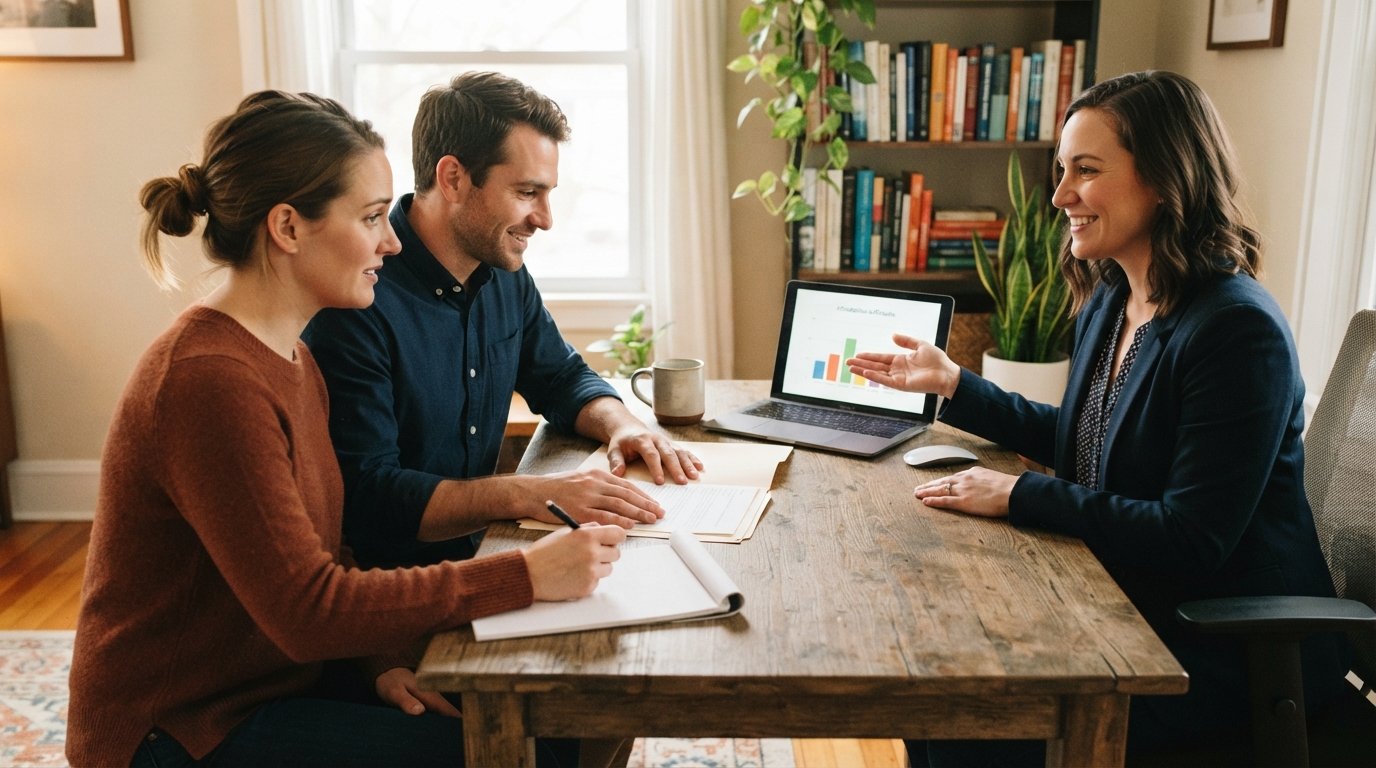
First time buyers hesitate because they do not yet trust the process or the person guiding it. Trust is not built with a rate sheet. It is built with clarity, consistency, and small commitments. On the first call, your goal is not to close a loan. Your goal is to earn the next conversation. That means listening more than pitching, answering the question behind the question, and ending every call with a specific, low-pressure next step.
Language matters here. Compare two openers. The first: "I saw you are interested in buying a home, let me tell you about our rates." The second: "You mentioned you are hoping to buy in the next few months. What is the part of the process that feels most confusing right now?" The second opener invites a real answer and positions you as a guide rather than a salesperson. Hesitant borrowers respond to guides.
Consistency compounds trust. If you promise to send a payment estimate by Tuesday, send it Monday. If you say you will check on a down payment assistance program, follow up with an answer even if the answer is "not eligible." Every kept promise is a deposit in the trust account. Every missed follow-up is a withdrawal, and first time buyers are quick to notice.
Small commitments also lower the barrier to action. Instead of asking a hesitant buyer to complete a full application, ask them to complete a five-minute pre-qualification. Instead of asking them to choose a realtor, offer to introduce them to two agents and let them pick. Each small yes makes the next yes easier, and it keeps momentum alive without pressure.
Follow-Up Frameworks That Move Hesitant Borrowers
Most first time buyer leads are not converted on the first call. They are converted across a structured follow-up sequence that mixes education, reassurance, and gentle urgency. The key is to make each touchpoint valuable on its own, so the prospect never feels hunted. A buyer who receives a useful text about down payment assistance programs is far more likely to answer your next call than one who receives a generic "just checking in" message.
A practical sequence looks like this. Day one: call and text within minutes of the lead arriving. Day two: send a personalized payment estimate based on their stated budget. Day four: share one relevant resource, such as a first time buyer checklist or a local assistance program. Day seven: call again with a specific question about their timeline. Day fourteen: offer a soft check-in that gives them an easy way to re-engage. Day thirty: send a market or rate update that keeps you top of mind without asking for anything.
Overlay this sequence with content that addresses the hesitation profile you identified. Credit-worried buyers get a short explanation of how pre-qualification works and why it does not damage their score. Affordability-worried buyers get a full monthly payment breakdown including taxes, insurance, and mortgage insurance. Commitment-worried buyers get a walkthrough of contingencies and the fact that pre-approval is not a contract. Personalization is not a nice-to-have here. It is the difference between a reply and a silence.
Live transfers deserve special handling. When a consumer is transferred to you in real time, they have already agreed to speak with a professional. Your job is to keep that momentum. Open with a thank-you, confirm the details they already shared, and move quickly to a specific next step. Do not restart the qualification from scratch. If your provider offers a buffer window before the call connects, use that time to review the consumer's stated needs so the conversation feels continuous rather than repetitive.
Handle the Most Common Objections
Hesitant borrowers rarely say "I am afraid." They say things like "I need to think about it," "my credit is not good enough," or "I will wait until rates drop." Each of these is a surface objection covering a deeper concern. Your response should acknowledge the surface statement, then gently uncover and address the real issue.
When a buyer says they need to think about it, ask what specifically they want to think through. The answer is usually a concrete question they have not asked yet. When they say their credit is not good enough, explain that many first time buyer programs accept lower scores than people assume, and offer to run a soft pre-qualification to find out. When they say they are waiting for rates to drop, reframe the decision: they can buy now and refinance later, but they cannot get back the equity they build while waiting.
Another common objection is fear of being pressured. First time buyers have often been warned by friends or family that lenders will push them into a loan they cannot afford. You can neutralize that fear directly by stating your process up front: no obligation, no hard credit pull without permission, and no pressure to move faster than they are comfortable. Transparency is a competitive advantage in a market where trust is scarce.
Measure and Improve Conversion Rates
Conversion is not a mystery. It is a set of numbers you can track and improve. Start with speed to first contact, because it is the single most predictive metric in lead conversion. Then track contact rate, qualification rate, application rate, and funded loan rate. Each stage tells you where leads are leaking and what to fix next.
If contact rates are low, your problem is likely timing or channel, not your script. If contact rates are high but applications are low, your problem is trust or clarity. If applications are high but funded loans are low, your problem may be lead quality or borrower readiness. Diagnosing the stage before changing the tactic prevents wasted effort.
Also review your lead sources against outcomes, not just volume. A source that delivers fifty leads a month with a two percent application rate may be less valuable than one that delivers fifteen leads with a fifteen percent rate. When you evaluate providers, ask about delivery speed, exclusivity options, filtering capabilities, and return policies. These operational details shape conversion long before a borrower ever hears your voice.
Turn Hesitation into Applications
Hesitant first time buyers are not a problem to overcome. They are a signal that the market still has room for professionals who educate, reassure, and follow through. The loan officers who win in this segment are not the ones with the lowest rates. They are the ones who answer the phone first, explain the process clearly, and stay present through the entire decision cycle.
If you want a steadier stream of first time buyer conversations, focus on lead quality, response speed, and a follow-up system that delivers value at every touchpoint. That combination converts hesitation into applications, and applications into funded loans. If you are ready to build that pipeline, reach out at (510)-663-7016 to talk through your options.