HECM for Purchase Leads: Expanding Your Reverse Mortgage Client Base
HECM for purchase leads expanding the reverse mortgage client base help loan officers reach senior buyers. Call (510)-663-7016 to start.
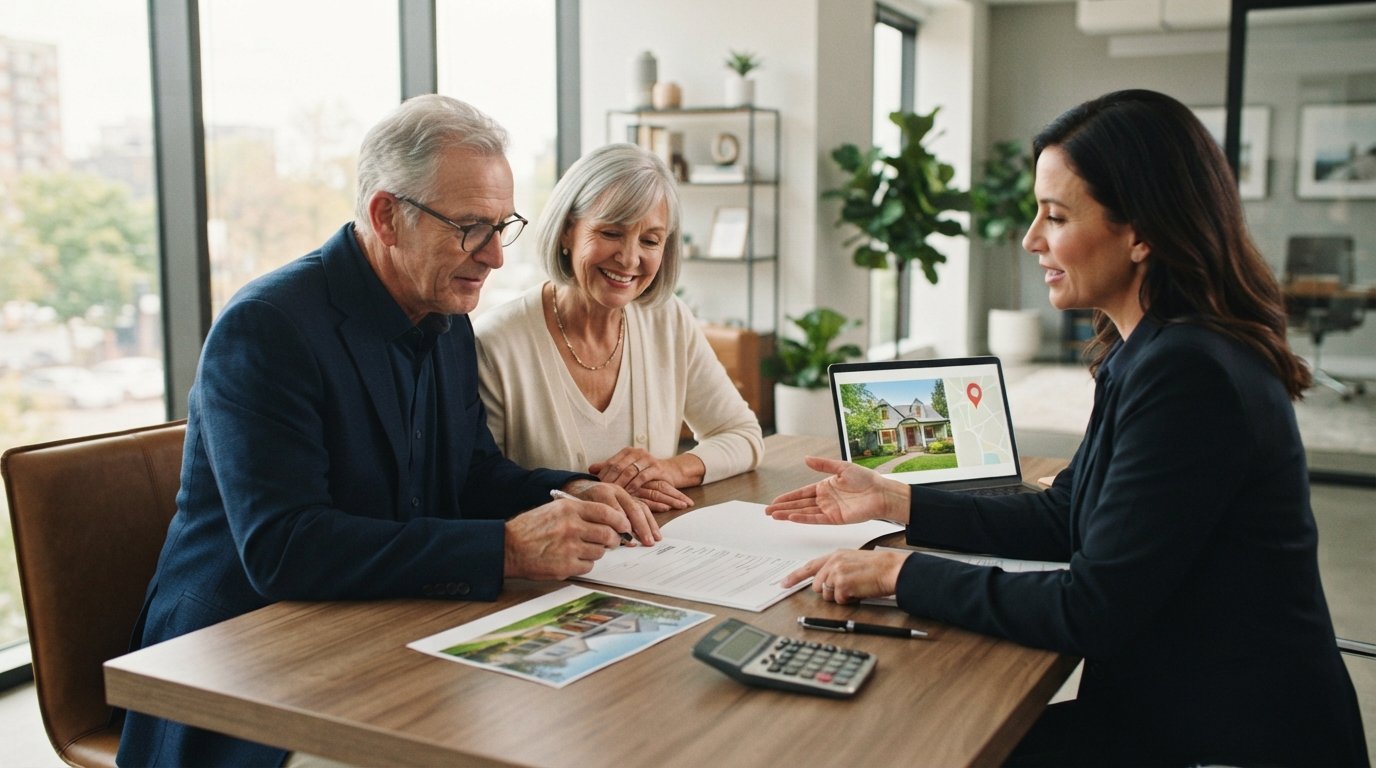
Reverse mortgage professionals know the traditional refinance market well: seniors tapping home equity to stay in place, pay off debt, or supplement retirement income. But a quieter, faster-growing segment is reshaping who the reverse mortgage client actually is. HECM for Purchase, the Federal Housing Administration program that lets buyers age 62 and older buy a new home with a reverse mortgage, is opening a pipeline of clients who are not refinancing at all. They are relocating, downsizing, and moving closer to family, and they need financing that conventional products rarely serve well. That shift is why HECM for purchase leads expanding the reverse mortgage client base has become a strategic priority for lenders, brokers, and loan officers who want to grow beyond the refinance treadmill.
The opportunity is real but easy to misread. HECM for Purchase is not simply a reverse mortgage with a different label; it is a purchase transaction with its own underwriting logic, its own down payment math, and its own set of consumer anxieties. Professionals who treat these leads like refinance prospects will waste time and money. Those who understand the distinct profile of the HECM purchase borrower, and who build the right referral and education infrastructure around it, can convert a steady stream of high-intent seniors into funded loans. This article breaks down how the product differs, how to qualify leads quickly, how to partner with senior-focused real estate agents, and how to address family concerns before they derail a deal.
Why HECM for Purchase Attracts a Different Borrower
A traditional reverse mortgage refinance is, at its core, a transaction with the current homeowner. The borrower already owns the property, has likely lived there for years, and is looking for a financial tool to improve cash flow or eliminate a mortgage payment. HECM for Purchase flips that model. The borrower is a homebuyer, often selling a long-held family home, and is using a reverse mortgage to buy the next one. The property is new to them, the transaction is a purchase, and the timeline is driven by real estate contingencies rather than a leisurely refinance decision.
That difference changes everything about lead qualification. A refinance lead may be months away from acting; a purchase lead is usually on a clock. They may have already listed their current home, made an offer on a new property, or signed a leaseback agreement. They often have a real estate agent involved and a moving date in mind. The urgency is higher, the documentation is more complex, and the stakes feel more personal because the decision is tied to a major life transition rather than a financial optimization.
There is also a demographic nuance. HECM for Purchase borrowers are frequently older seniors, often in their late 60s to 80s, who are downsizing or moving to be near adult children. They may be widowed, recently retired, or managing a fixed income. Many are cash-rich from the sale of a previous home but want to preserve liquidity rather than sink every dollar into a new property. This is not a distressed borrower profile; it is a strategic one. Understanding that distinction helps loan officers frame the conversation around preserving assets and maintaining financial flexibility rather than solving a problem.
Because the purchase borrower is often working with a real estate agent, the lead source matters. Leads that come from senior-focused real estate partnerships or from consumers actively searching for downsizing options tend to be more informed and further along in the process. MortgageLeads.com provides reverse mortgage leads that can be filtered by geography and demographic criteria, which helps lenders target markets with a high concentration of age-eligible homeowners and active senior relocation activity.
Qualifying Signals: Age, Down Payment Capacity, and Relocation Intent
The first filter for any HECM for Purchase lead is age. At least one borrower on the loan must be 62 or older, and the program requires that the borrower use the home as a principal residence. That sounds simple, but in practice, leads often include couples where one spouse is under 62, adult children inquiring on behalf of a parent, or seniors who are exploring options for a second home. Screening for age eligibility and primary residence intent early saves hours of follow-up.
Down payment capacity is the second critical signal. HECM for Purchase requires a down payment that is typically larger than what many seniors expect, and the exact amount depends on the age of the youngest borrower, current interest rates, and the appraised value of the property. In general, the older the borrower, the lower the required down payment percentage. A 62-year-old might need a down payment in the mid-40s as a percentage of the purchase price, while an 80-year-old might need something closer to the low 30s or high 20s. These numbers shift with market conditions, so loan officers should verify current requirements rather than quoting stale figures.
Relocation intent is the third signal, and it is often the most predictive of conversion. A lead who has already decided to move, who has a target area in mind, and who is working with a real estate agent is far more likely to close than someone who is simply curious about the program. Questions that surface relocation intent include whether the prospect has listed their current home, whether they have a timeline for moving, whether they need to be near family or medical care, and whether they have spoken with a real estate agent. Leads that answer these questions affirmatively should move to the top of the follow-up queue.
A practical qualification framework looks like this:
- Age and occupancy: Confirm at least one borrower is 62 or older and that the new home will be the principal residence.
- Down payment readiness: Ask whether the prospect has funds available from a home sale, savings, or family gifts, and explain that the required down payment varies by age and property.
- Relocation timeline: Identify whether the prospect is actively looking, planning to list, or just exploring, and prioritize active buyers.
- Real estate involvement: Determine whether an agent is already engaged, because agent partnerships accelerate the transaction and reduce fall-through risk.
- Family awareness: Gauge whether adult children or heirs are aware of the plan, since family objections are a common source of delay.
Once these signals are captured, the follow-up process should be fast and consultative. HECM for Purchase is not a product most seniors understand off the shelf, so the first conversation should educate rather than pitch. Explaining how the loan works, how the down payment is calculated, and how the borrower retains title can move a hesitant prospect forward. For teams that need to verify lead quality before investing time, resources like a mortgage lead verification and quality assurance guide can help standardize intake and reduce wasted outreach.
Partnering with Senior-Focused Realtors to Multiply Lead Value
HECM for Purchase is a purchase product, which means real estate agents are natural allies. Senior-focused realtors, particularly those with designations like Seniors Real Estate Specialist (SRES), work with downsizing clients every day and often encounter buyers who want to buy without tying up all their cash. These agents are not mortgage experts, and most do not proactively raise reverse mortgages with clients. That creates an opening for loan officers who can educate agents and position themselves as the go-to financing resource for 62-plus buyers.
The most effective partnerships are built on education, not lead begging. Offer to host a lunch-and-learn for an agent's team on how HECM for Purchase works, what the down payment looks like at different ages, and which buyer profiles are a good fit. Provide a one-page checklist that agents can use to spot candidates: clients who are selling a long-held home, who want to stay in a similar price range, who value liquidity, or who have expressed concern about draining savings. When agents understand the product, they refer naturally because it helps them close sales that might otherwise stall.
Complementing purchased leads with agent referrals creates a compounding pipeline. Purchased HECM leads fill the top of the funnel with consumers who have expressed interest, while agent partnerships generate warm introductions from a trusted advisor. The two sources reinforce each other: an agent referral can validate a purchased lead in the same market, and a purchased lead can be routed to an agent partner who specializes in the prospect's target area. Over time, this dual-source strategy reduces reliance on any single channel and improves close rates because prospects arrive with more context and trust.
It also helps to think about the agent relationship as a two-way street. Agents want financing partners who communicate clearly, set realistic expectations, and do not create surprises at closing. Loan officers who master HECM for Purchase timelines and documentation become valuable to agents because they reduce friction in transactions that could otherwise fall apart. That reputation spreads through brokerage offices and senior-focused networks, which is ultimately how HECM for purchase leads expanding the reverse mortgage client base becomes a durable growth engine rather than a one-time campaign.
Educational Messaging That Addresses Heirs and Family Concerns Early
One of the biggest obstacles in HECM for Purchase is not underwriting or down payment; it is family objection. Adult children often worry that a reverse mortgage will consume their inheritance, that the parent will lose the home, or that the loan is a scam. These concerns are understandable, and they surface in almost every purchase transaction involving a senior borrower. Loan officers who wait until the eleventh hour to address them often see deals stall or collapse.
The fix is to bring family into the education process early. During the initial consultation, ask whether the prospect has discussed the purchase with their children and whether they would like to include them in a follow-up call. Offering a family-friendly explainer, a short video, or a one-page summary that covers the basics can preempt misinformation. Key points to communicate include the fact that the borrower retains title, that the loan does not have to be repaid until the borrower sells, moves out permanently, or passes away, and that any remaining equity belongs to the estate or heirs. These are the questions heirs actually ask, and answering them proactively builds trust.
It also helps to frame HECM for Purchase as a financial planning tool rather than a last resort. Many seniors use it to preserve cash reserves, avoid depleting retirement accounts, or maintain a financial cushion for health care and other expenses. When heirs understand that the decision is about liquidity and lifestyle rather than desperation, resistance often softens. Loan officers who can speak to these planning benefits, without overpromising, position themselves as trusted advisors rather than product salespeople.
For lenders and brokers sourcing leads at scale, the messaging should start before the first call. Lead nurturing sequences that include educational content about HECM for Purchase, family conversations, and the difference between a reverse mortgage refinance and a purchase loan can warm prospects and reduce surprises. A platform like PingPost.Exchange can support real-time lead distribution and routing so that the right prospect reaches the right loan officer quickly, which matters in purchase transactions where timing is tight. Combining fast lead delivery with thoughtful education creates a better borrower experience and higher conversion.
Building a Repeatable HECM for Purchase Lead Strategy
Scaling a HECM for Purchase pipeline requires more than buying leads and hoping for the best. It requires a system: clear qualification criteria, fast follow-up, agent partnerships, and family-inclusive education. The good news is that the market is large and underserved. Millions of homeowners are entering the 62-plus age bracket, and many of them will consider relocating in the coming years. Most mortgage professionals are not equipped to serve them well, which means the loan officers who build expertise now will have a durable competitive advantage.
A repeatable strategy starts with sourcing. Purchase reverse mortgage leads should be filtered for age eligibility, geography, and expressed interest in downsizing or relocating. MortgageLeads.com offers reverse mortgage leads that can be filtered by geographic and demographic criteria, and the platform supports multiple delivery methods, including real-time leads and live transfers, so teams can choose the format that fits their workflow. Pricing and availability can change, so it is worth checking current product pages before planning a campaign.
From there, the process should be tight. Respond to new leads within minutes, not hours. Use a short discovery call to confirm age, down payment readiness, relocation timeline, and family awareness. Send an educational follow-up that the prospect can share with their children. Introduce a real estate agent partner if the prospect does not already have one. And keep the conversation focused on the outcome the borrower wants, which is usually a comfortable, affordable home near family or in a preferred community.
Finally, measure what matters. Track conversion by lead source, time to first contact, and family-involvement rate. Teams that review these metrics monthly can refine their targeting and messaging, and they can identify which agent partnerships and lead sources produce the best results. Over time, this discipline turns HECM for purchase leads expanding the reverse mortgage client base from a promising idea into a reliable growth channel. The seniors are out there, the product fits their needs, and the professionals who show up with clarity and empathy will earn their business.