How to Build Consistent Mortgage Lead Flow Month to Month
Build consistent mortgage lead flow month to month with a diversified channel mix, fast follow-up, and weekly tracking. Call (510)-663-7016 to get started.
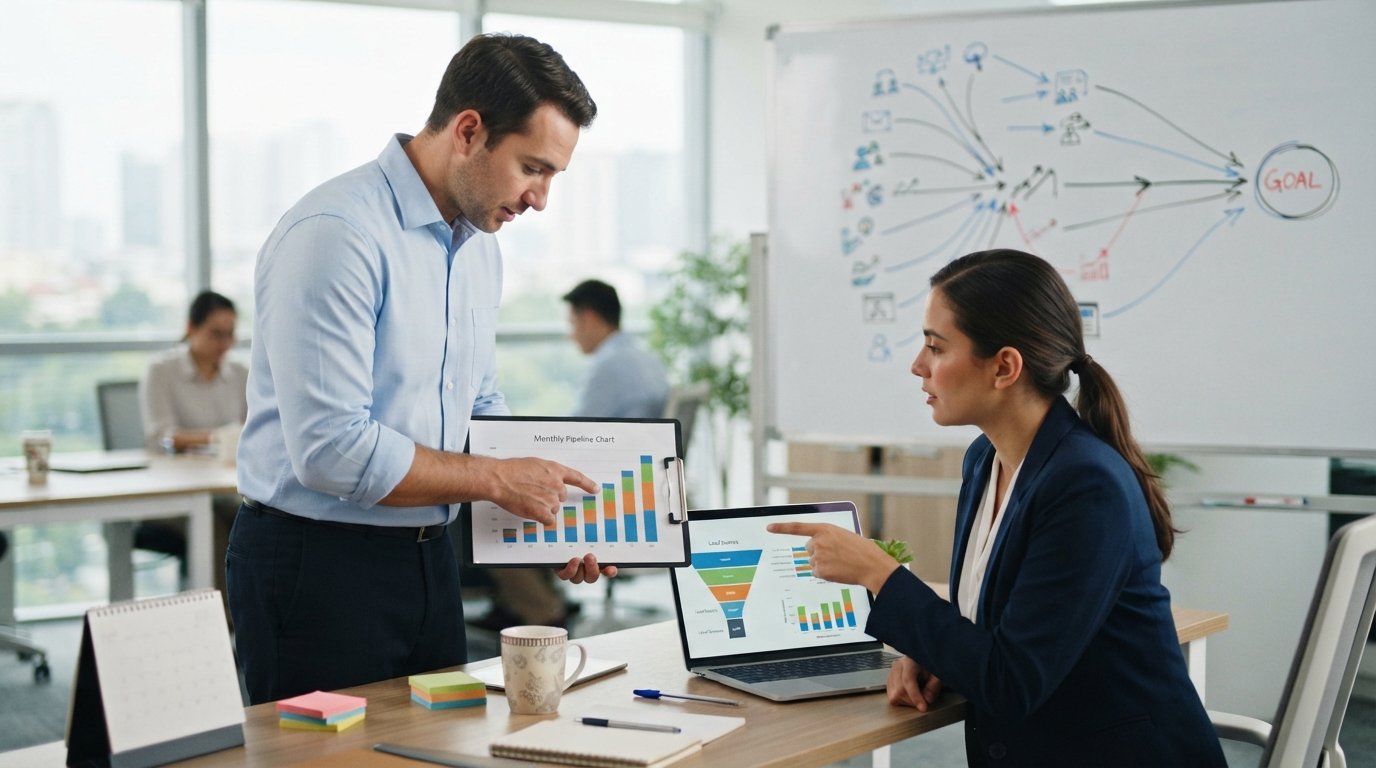
Ask any loan officer what keeps them up at night, and you will hear the same answer: the feast or famine cycle. One month the pipeline overflows, the next month it runs dry, and the scramble begins again. That volatility is not bad luck. It is the predictable result of relying on one or two lead sources that fluctuate with the market, the season, and the algorithm. Building consistent mortgage lead flow month to month is a systems problem, not a hustle problem, and the professionals who solve it treat lead generation like a machine with multiple fuel lines rather than a lottery ticket.
This guide breaks down how to build consistent mortgage lead flow month to month using a framework that combines diverse acquisition channels, disciplined conversion follow-up, rigorous tracking, and the right B2B lead partner. Whether you are a solo loan officer in Portland, a broker in Denver, or part of a multi-state lending team, the principles scale. The goal is simple: a pipeline that produces a predictable number of funded loans every single month, regardless of what rates do or when purchase season peaks.
Start With a Lead Math Model, Not a Marketing Tactic
Most mortgage professionals jump straight to tactics: buy leads here, run ads there, ask for referrals everywhere. That is backwards. Before you spend a dollar, you need to know how many leads you actually require each month to hit your funding goal. This is basic funnel math, and it removes the guesswork from every decision that follows.
Suppose your target is four funded loans per month. If your lead-to-application rate is 20 percent and your application-to-funding rate is 25 percent, then you need roughly 80 leads per month to close four loans. Those numbers are illustrative, and yours will differ by product, geography, and speed to contact, but the formula forces clarity. Once you know the number, you can divide it across channels, set budgets, and spot shortfalls weeks before they hit your commission check.
Build the model in a spreadsheet and update it monthly with real data. Track leads received, contact rate, application rate, and funded rate for each source separately. A refinance lead from a live transfer call behaves very differently than a shared online form lead, and blending the two hides the truth. When you know that one channel converts at triple the rate of another, you can shift spend with confidence instead of guessing.
- Leads received per channel, tracked weekly
- Contact rate within the first five minutes and first hour
- Application rate and pull-through to processing
- Funded loans and average revenue per lead by source
- Cost per funded loan, your single most important metric
This model becomes the backbone of everything else. It tells you when to buy more leads, when to pause a campaign, and when a dip in funded volume is a lead supply problem versus a follow-up problem. Without it, you are marketing on vibes, and vibes do not pay overhead.
Diversify Lead Sources So No Single Channel Controls Your Month
The fastest way to break the feast or famine cycle is to stop depending on one source. If all your volume comes from purchased internet leads, a price change at that vendor can wipe out your month. If everything comes from referrals, a slow purchase season can do the same. Consistency comes from stacking three to five channels that respond to different market conditions.
Purchased leads remain the most controllable channel because you can dial volume up or down based on your capacity and your funnel math. A quality B2B provider like MortgageLeads.com offers verified, real-time leads across refinance, new purchase, home equity, and reverse mortgage products, with filters for geography and demographics and options for exclusive leads, shared leads, pay-per-call, and live transfers. That flexibility matters because it lets you match lead type to your strengths. If your team excels on the phone, live transfers with a 90-second buffer and a stated 100 percent contact rate may outperform web forms. If you prefer working inbound inquiries on your own schedule, exclusive form leads give you room to nurture.
Around that purchased foundation, layer organic and referral channels that compound over time. A first-time buyer education series, a realtor partnership program, and a past-client check-in cadence all generate leads at a lower marginal cost, though they take longer to mature. The point is not to replace purchased leads but to insulate yourself from any single source going quiet.
Here is a practical channel mix that many top producers use. Adjust the percentages to fit your market and budget, but keep at least three channels active at all times.
- Purchased leads (exclusive or live transfer) for immediate, scalable volume
- Realtor and agent referrals for high-intent purchase business
- Past client database reactivation for refinance and home equity opportunities
- Organic content and local SEO for long-term inbound flow
- Paid social or search for seasonal spikes and product launches
When one channel dips, the others carry the month. That is the entire logic of diversification, and it is the difference between a predictable pipeline and a constant emergency.
Match Lead Type to Product and Market Conditions
Consistency also depends on buying the right lead for the right moment. A purchase lead and a refinance lead respond to completely different triggers, and the mortgage professionals who understand this buy strategically rather than broadly. When rates drop, refinance and home equity inquiries surge, and speed to contact becomes the deciding factor. When rates hold steady, purchase and first-time buyer leads carry the pipeline.
If you want to build a durable pipeline, it also pays to understand how to generate first-time home buyer mortgage leads, since that segment tends to be less rate-sensitive and more relationship-driven. First-time buyers need education, hand-holding, and trust, which means a lead that looks mediocre on paper can convert beautifully with the right nurture sequence. Meanwhile, a reverse mortgage lead from a senior audience requires a different script entirely, and home equity leads often convert fastest through a simple, low-friction offer.
The practical takeaway is to segment your lead purchases by product and by season, then weight your budget toward whatever is converting best that quarter. Review the mix monthly. A channel that produced strong refinance volume last spring may underperform this spring if rates moved, and your budget should move with it.
Build a Speed-to-Lead and Follow-Up Engine
Lead flow without conversion discipline is just expensive noise. Study after study in mortgage and insurance sales shows the same pattern: contact within five minutes dramatically increases the odds of a conversation, and the odds fall off a cliff after the first hour. If your team takes half a day to call a new lead, you are paying full price for a fraction of the results.
Design a follow-up cadence that runs on autopilot. Every new lead should receive an immediate call attempt, a text message, an email, and a second call within the first 24 hours. From there, a structured sequence over the next two weeks keeps you present without becoming a nuisance. Most leads do not buy on day one, and the professionals who win are the ones still following up on day twelve while everyone else quit on day two.
Speed and persistence are only half the equation. The other half is routing. Leads should flow directly into your CRM with source tags, so you can see which channel produced them and how they convert. If your provider supports API integration into third-party CRMs and quoting engines, use it. Manual data entry kills momentum and introduces errors that cost you deals. When a lead arrives and the first call happens before the consumer has time to shop three other lenders, you have already won most of the battle.
Track Weekly, Adjust Monthly, and Never Stop Testing
Consistency is a byproduct of measurement. Set a weekly review where you look at lead volume, contact rate, and appointments booked. Set a monthly review where you analyze cost per funded loan by channel and reallocate budget accordingly. This rhythm catches problems early. If your contact rate drops from 60 percent to 40 percent, you know within a week, not within a quarter.
Testing should be continuous but disciplined. Change one variable at a time: a new script, a different lead type, a revised landing page, a fresh follow-up cadence. Keep what works, discard what does not, and document the results so your team does not repeat old mistakes. Over a year, these small compounding improvements turn an inconsistent pipeline into a dependable one.
It also helps to borrow proven systems from adjacent industries where lead response is life or death for the business. For example, legal lead generation platforms such as AttorneyLeads have refined real-time, pre-screened lead delivery and follow-up workflows that translate surprisingly well to mortgage sales. The core discipline is identical: verify intent, contact fast, and route the lead to the right person immediately.
Use a Lead Exchange to Smooth Seasonal Gaps
Even the best-run mortgage operation faces seasonal gaps. Purchase volume cools in winter, refinance waves come and go, and local market quirks create unpredictable weeks. A lead exchange platform helps smooth those gaps by giving you access to a broader network of buyers and sellers, so you can source volume when your usual channels slow down and adjust your buying caps when demand spikes.
MortgageLeads.com operates as both a lead provider and a lead exchange, which means you can buy verified leads directly or tap into a real-time marketplace to supplement your pipeline. Representative pricing ranges from a few dollars for home equity leads to premium rates for refinance live transfers, and the platform has been operating in financial lead generation for over 13 years. Because prices, filters, and return rules can change, always confirm current packages on the product pages before committing budget.
The strategic value of an exchange is optionality. When your primary channel underdelivers in a given month, you have a second lever to pull without rebuilding your entire marketing plan from scratch. That single capability is often what separates a pipeline that wobbles from one that holds steady all year.
Putting the System Together
Building consistent mortgage lead flow month to month comes down to four moving parts working together: a lead math model that tells you how many leads you need, a diversified channel mix that protects you from any single source failing, a speed-to-lead and follow-up engine that converts what you buy, and a weekly and monthly review cadence that keeps the whole machine honest. None of these pieces is glamorous on its own, but together they replace the emotional rollercoaster of feast or famine with something far more valuable: predictability.
Start with the math this week. Add one new channel this month. Tighten your follow-up sequence before your next campaign. Within a quarter, you will not just have more leads, you will have a repeatable system that produces them on schedule, month after month, in any rate environment.