Jumbo Loan Purchase Leads Strategy for High Net Worth Borrowers
Exclusive jumbo loan purchase leads strategy for high net worth borrowers: filter by loan size and geography, qualify on reserves, and win advisor referrals. Call (510)-663-7016.
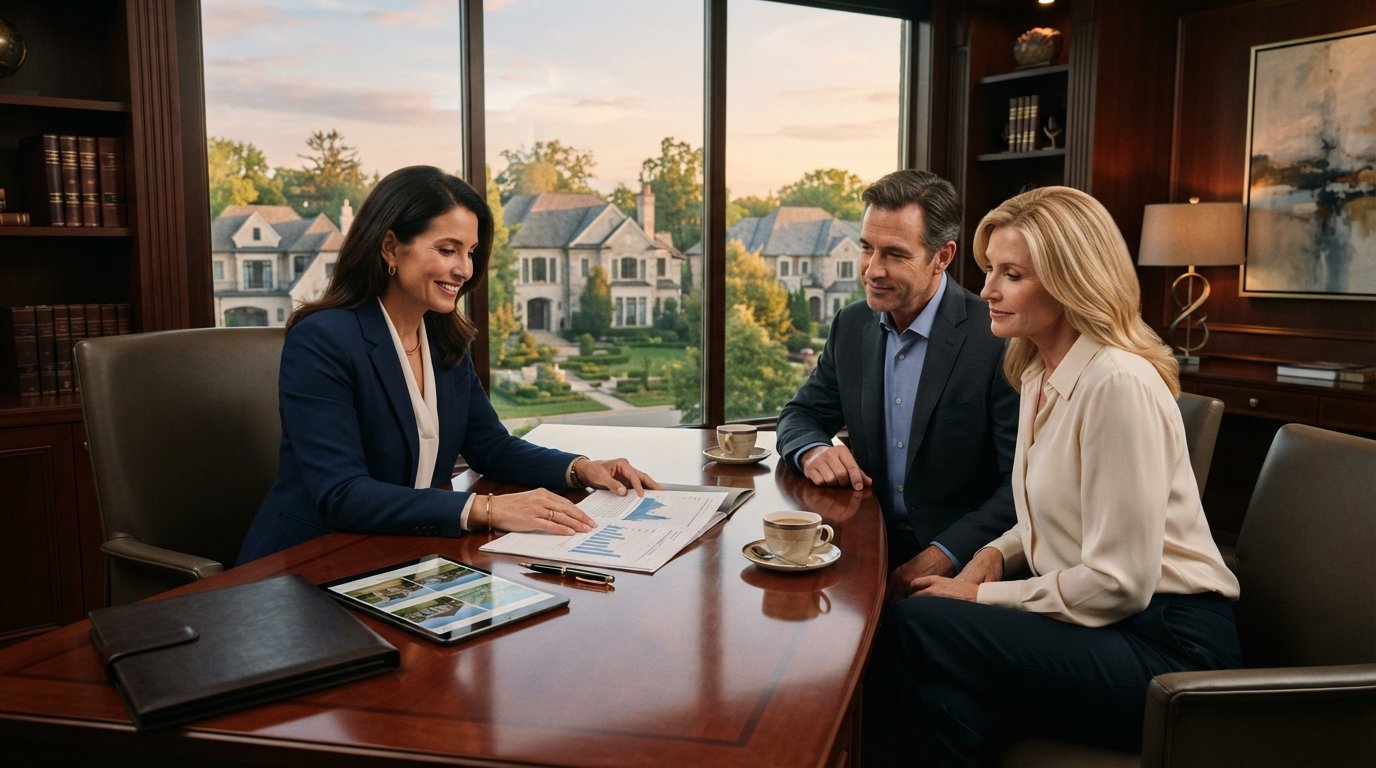
A $2.5 million purchase in a competitive enclave rarely starts with a Google search for "mortgage rates." It starts with a wealth manager, a private banker, or a realtor who knows the buyer's balance sheet. That single behavioral fact reshapes everything about how you source, qualify, and convert jumbo loan purchase leads strategy for high net worth borrowers. Affluent buyers do not shop the way first-time borrowers do. They compare advisors, not rate tables. They expect white-glove responsiveness, discretion, and a lender who understands complex income streams. If your lead strategy treats a $3 million purchase the same way it treats a $350,000 one, you will burn budget on contacts that never convert and miss the families who would happily pay for certainty.
This guide breaks down the operational playbook: how to filter for jumbo thresholds and geography, which qualifying signals separate a real prospect from a curiosity seeker, why shared delivery almost always fails at this loan size, and how to coordinate follow-up with the wealth managers and realtor partners who actually control the relationship. The tactics here are built for loan officers, brokers, and lending institutions that want a repeatable pipeline rather than a pile of unworked names.
What Makes Jumbo Borrowers Different in a Lead Filter
The first filter is mechanical: loan amount. Jumbo thresholds move with conforming limits, so any lead source you use should let you set a minimum loan amount well above the conforming ceiling for the target county. A borrower shopping at $1.2 million in a high-cost metro behaves very differently from one shopping at $600,000 in a Midwest suburb. Geography matters just as much. High-net-worth purchase activity clusters in specific ZIP codes, school districts, and second-home corridors. If your filter cannot isolate those geographies, you are paying for volume you cannot serve.
But the filter that separates professionals from amateurs is the one most lead buyers ignore: intent stage. A jumbo buyer rarely submits a generic form months before making an offer. They engage when they have identified a property, when a realtor has pre-negotiated terms, or when a wealth manager has flagged a liquidity event. That means recency of inquiry matters more at this loan size than at any other. A three-day-old jumbo lead is worth dramatically more than a three-week-old one, because the buyer's timeline is compressed and their advisor network is already active.
When you configure filters on a platform like MortgageLeads.com, the practical setup looks like this:
- Minimum loan amount set above the conforming limit for every county you serve, not a single national number.
- Geography narrowed to affluent ZIP codes, second-home markets, and new-construction enclaves where jumbo activity concentrates.
- Lead type restricted to new purchase rather than refinance, since jumbo purchase timelines are shorter and more advisor-driven.
- Delivery method chosen for speed (live transfer or real-time exclusive) rather than batch email.
That last point deserves emphasis. The difference between reaching a jumbo buyer in ninety seconds and reaching them in ninety minutes is often the difference between winning the file and learning about it after close. Real-time delivery is not a luxury at this tier; it is the baseline expectation of the borrower and their advisor team.
Qualifying Signals That Matter for Jumbo Files
Once a lead lands, the qualification conversation is fundamentally different from a conventional pre-qualification. Jumbo underwriters care about reserves, asset composition, and documentation readiness in ways that conventional guidelines do not. A borrower with $4 million in liquid assets but irregular K-1 income can be an excellent jumbo client, provided the file is assembled correctly. A borrower with a strong salary but thin post-closing reserves can stall at the eleventh hour. Your first call should surface which scenario you are dealing with.
The signals worth capturing early fall into three buckets. First, reserves: how many months of principal, interest, taxes, and insurance can the borrower document after closing, and in what account types? Second, asset composition: are the funds liquid, vested, or tied to a business sale or partnership distribution that has a defined timeline? Third, documentation readiness: does the borrower already have tax returns, entity documents, and a relationship with a CPA who can turn around letters quickly? Borrowers who answer these questions crisply are ready to transact. Borrowers who deflect are usually months away from a real purchase.
A simple qualification framework keeps your team consistent:
- Confirm the purchase timeline and whether a property is under contract or identified.
- Ask for post-closing reserve targets and the account types holding those reserves.
- Identify any non-W-2 income and whether the supporting documentation is current.
- Confirm who else is advising the buyer (wealth manager, CPA, realtor) and whether you can be introduced.
That fourth step is where most loan officers leave money on the table. The advisor network is not a nice-to-have; it is the distribution channel. When a buyer names their wealth manager, you have an opening to become the lender of record for every future transaction that advisor touches. Treat that introduction as a qualification outcome, not an afterthought.
Why Shared Leads Underperform for Jumbo Purchase Files
Shared leads work when the product is commoditized and speed to contact is the only differentiator. Neither condition holds at jumbo loan sizes. A high-net-worth buyer receiving four calls in ten minutes from four different lenders does not feel served; they feel processed. The advisor who referred them looks careless for putting them in that position. Even if you win the file, you have damaged the relationship that generated it, and that relationship is worth more than any single commission.
Exclusive delivery changes the economics in a way that is easy to underestimate. When you are the only lender contacting the buyer, your first conversation is consultative rather than competitive. You can ask about reserves and entity structure without signaling that three competitors are doing the same. You can coordinate timing with the realtor instead of racing other lenders to a pre-approval letter. And you can price the loan based on the actual risk profile rather than guessing at what a competitor might quote. For jumbo purchase leads, exclusive delivery is not a premium upsell; it is the minimum viable format.
Live transfers deserve particular attention here. A warm transfer from a lead platform to your loan officer, with the borrower already briefed on who is calling and why, compresses the trust-building phase from days to minutes. MortgageLeads.com structures live transfers with a short buffer so the borrower is genuinely expecting the call, which matters enormously when the person on the other end is deciding whether to hand over a multi-million-dollar financial picture. If you are evaluating delivery formats, prioritize live transfer and real-time exclusive over shared or batch delivery for any file above the conforming limit.
Coordinating Follow-Up With Wealth Managers and Realtor Partners
The jumbo purchase does not belong to the lender. It belongs to a small circle of advisors, and the lender who integrates into that circle wins repeat business. Realtors in affluent markets control access to inventory and often know about a purchase before the buyer has spoken to any lender. Wealth managers control the liquidity conversation and can flag a sale of concentrated stock, a partnership distribution, or a trust distribution months before it becomes a mortgage application. Your follow-up strategy should treat both as partners, not as referral sources to be managed.
Practically, this means building a cadence that includes the advisor network from day one. When a jumbo lead arrives, your first call is to the borrower, but your second call is to the realtor if one is named, to confirm timing and pre-approval expectations. A short weekly update to the wealth manager, framed around documentation status rather than sales pressure, keeps you top of mind for the next transaction. Over time, this cadence turns a single purchase lead into a pipeline of affluent buyers who arrive pre-qualified by people you already trust.
For lenders expanding into new affluent markets, the same logic applies at the state level. If you are building a presence in the Southeast, the playbook in this guide on Florida mortgage purchase leads for lenders shows how geographic filtering and advisor coordination work together in a high-net-worth purchase market. The principles transfer directly: filter for loan size and ZIP code, deliver in real time, and integrate with the advisors who control the relationship.
Building a Repeatable Jumbo Lead Workflow
The difference between a lead strategy that produces occasional jumbo files and one that produces a reliable pipeline is process discipline. Affluent buyers do not respond to volume; they respond to precision. That means your workflow should be documented, timed, and measured at every stage, from lead receipt to pre-approval to close. Without that discipline, even exclusive jumbo leads degrade into unworked names within a week.
A workable workflow has four stages. First, intake: every jumbo lead is assigned to a named loan officer within minutes, not routed to a general queue. Second, discovery: the qualification framework above is completed on the first call, with reserve and asset details captured in the CRM. Third, advisor integration: the realtor and wealth manager are identified and contacted within twenty-four hours. Fourth, documentation: the file is assembled to jumbo underwriting standards before any property-specific deadline creates pressure. Each stage should have an owner and a time target.
Measurement matters as much as process. Track contact rate, qualification rate, pre-approval rate, and close rate separately for jumbo leads versus conventional leads. If contact rate is high but qualification rate is low, your filters are too broad. If qualification is high but pre-approval is low, your discovery call is missing documentation signals. If pre-approval is high but close rate is low, your advisor coordination is failing. These four metrics tell you where to adjust the strategy rather than guessing.
It also helps to diversify your sourcing beyond mortgage-specific channels. Affluent borrowers often surface first in insurance and financial planning conversations, where life events like a business sale or a trust distribution trigger a purchase. Platforms such as BestInsuranceLeads connect agents with verified, high-intent consumer leads across life, home, and auto insurance, and the same households that generate insurance inquiries frequently generate jumbo purchase activity. Coordinating with insurance and wealth advisors gives you an early signal that a mortgage-specific lead source will never capture on its own.
Common Mistakes That Undermine Jumbo Lead ROI
The most expensive mistake in jumbo lead buying is treating the lead as a transaction rather than an introduction. Loan officers who call a high-net-worth buyer with a rate quote and a pre-qualification pitch lose the file to the lender who calls with questions about reserves and entity structure. The buyer is not shopping for the cheapest loan; they are shopping for the advisor who will not create problems at underwriting. Lead with competence, not price.
The second mistake is underinvesting in follow-up speed. Jumbo buyers move quickly once they have identified a property, and their advisor network expects the lender to keep pace. A lead that sits in a queue for an hour is effectively cold at this tier. The third mistake is failing to close the loop with the realtor and wealth manager after the file funds. A thank-you call and a brief summary of what worked well costs nothing and generates the next introduction. The fourth mistake is measuring success by lead volume rather than funded loans. At jumbo loan sizes, five well-qualified exclusive leads will outperform fifty shared leads every quarter.
Finally, avoid the temptation to apply conventional lead scoring to jumbo files. A borrower with a 720 credit score and $3 million in liquid reserves is a stronger jumbo candidate than a borrower with an 800 score and thin post-closing reserves. Score on assets, reserves, and documentation readiness, not on credit alone. That single adjustment will change which leads your team prioritizes and, over time, which files actually close.
High-net-worth borrowers reward lenders who understand their world: complex income, advisor networks, and a low tolerance for friction. A jumbo loan purchase leads strategy for high net worth borrowers succeeds when it is built around exclusive delivery, real-time contact, and genuine coordination with the wealth managers and realtors who control the relationship. Get those three elements right, and the pipeline compounds. Get them wrong, and no amount of lead volume will compensate.