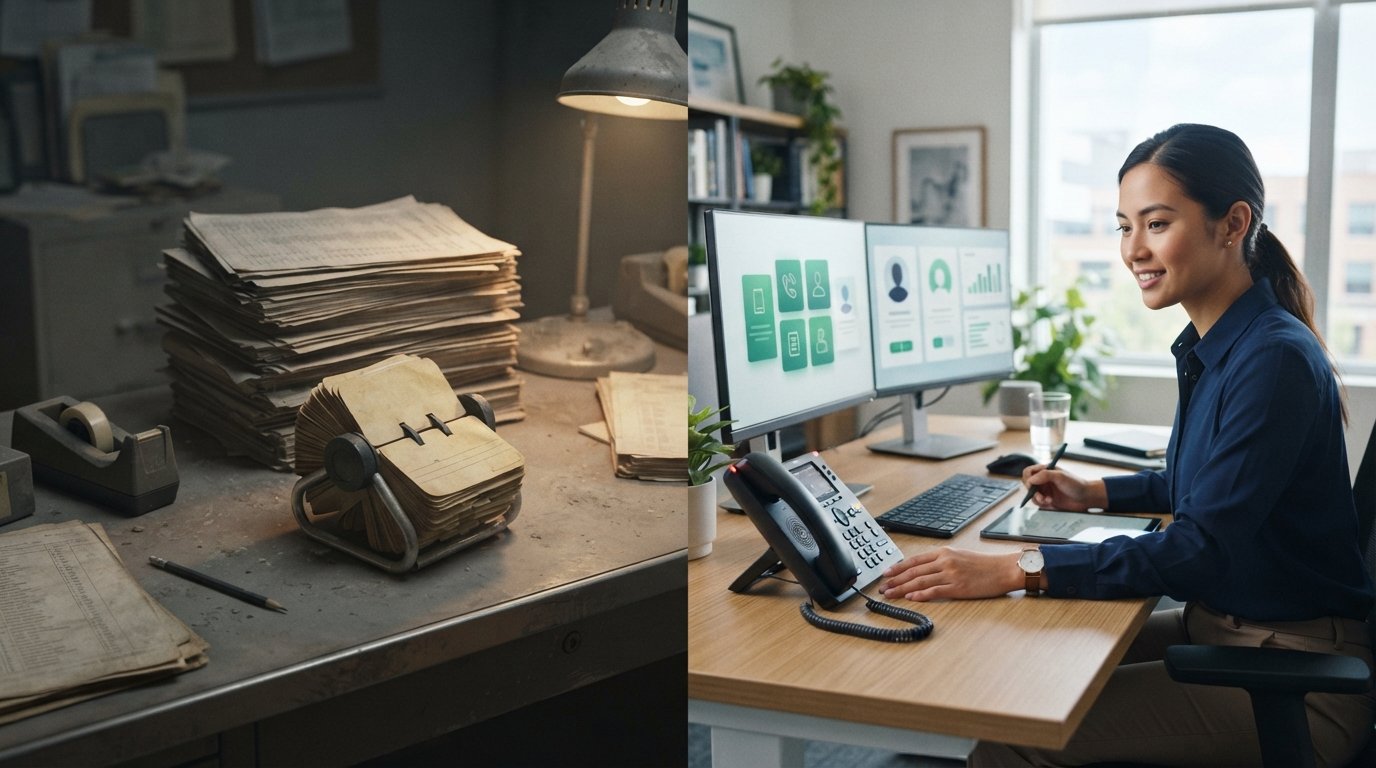
Mortgage Brokers Email List vs Real Time Mortgage Leads
Compare mortgage brokers email list versus real time mortgage leads and discover which drives higher conversion with less compliance risk. Call (510)-663-7016 to get started.
By Elara Moonridge
Mortgage brokers and loan officers face a constant choice: buy a static email list or invest in real-time mortgage leads. The decision shapes your pipeline, your compliance risk, and your return on investment. A purchased email list feels cheap and easy, but it often delivers low intent, poor contact rates, and legal exposure. Real-time leads, by contrast, connect you with consumers who have just expressed interest and are ready to talk. This article breaks down the mortgage brokers email list versus real time mortgage leads debate so you can choose the strategy that actually funds loans.
What a Purchased Email List Really Delivers
A mortgage brokers email list is typically compiled from third-party data sources, past inquiries, or scraped public records. The seller promises thousands of contacts for a one-time fee. On paper, the cost per contact looks tiny. In practice, the list is a snapshot of people who may or may not have any current mortgage need. Many on the list never consented to hear from you, and some addresses are outdated or belong to spam traps.
The core problem is intent. A person who downloaded a generic mortgage guide two years ago is not the same as someone actively shopping for a refinance today. When you send a cold email to a purchased list, you are interrupting strangers rather than responding to a request for help. Response rates for cold email to purchased lists often fall below 1 percent, and the few replies may be unqualified or even hostile.
Consider the typical lifecycle of a purchased list. You buy 5,000 email addresses for a few hundred dollars. You craft a polished email campaign. You send it out and wait. The first batch yields a handful of opens, maybe one or two clicks, and zero applications. The second send gets flagged as spam by internet service providers because recipients mark it as unwanted. Your domain reputation takes a hit, and future legitimate emails land in junk folders. The list becomes a liability rather than an asset.
Why Consent and Intent Matter in Mortgage Marketing
Mortgage marketing is regulated, and for good reason. Consumers share sensitive financial information, and regulators expect that their data is handled with care. When you email a purchased list, you cannot prove that the recipients opted in to receive marketing from you. Under laws like the CAN-SPAM Act, the Telephone Consumer Protection Act (TCPA), and state privacy statutes, sending unsolicited commercial email to a list without consent can trigger penalties. The risk is not hypothetical: class-action lawsuits against mortgage companies for email and text marketing violations are common, and defense costs alone can dwarf any savings from a cheap list.
Real-time mortgage leads operate on a different model. Consumers fill out a form or call a number, explicitly requesting information about a mortgage product. They agree to be contacted by a lending professional. That consent is documented, timestamped, and tied to a specific inquiry. When you buy a real-time lead from a platform like MortgageLeads.com, you receive a consumer who is expecting your call or email. The intent is fresh, and the consent is verifiable.
This difference in consent changes everything about your outreach. Instead of introducing yourself to a stranger, you are following up on a request the consumer just made. You can reference the specific product they asked about, which builds trust and improves conversion. And because the lead is real-time, you are often the first professional to reach out, giving you a significant advantage over competitors who wait hours or days.
Real-Time, Intent-Verified Leads: The Conversion Advantage
Real-time mortgage leads are delivered the moment a consumer expresses interest. That immediacy is critical in mortgage lending, where attention spans are short and consumers often contact multiple providers. Studies consistently show that contacting a lead within the first five minutes dramatically increases the chance of a conversation and a conversion. With a purchased email list, you have no idea when or why the contact opted in, so your timing is always off.
Intent verification further separates real-time leads from static lists. Reputable lead providers like MortgageLeads.com verify that the consumer is genuinely interested in a mortgage product, not just clicking a random ad. They may use phone verification, form validation, or behavioral checks to confirm intent. The result is a lead that is far more likely to answer your call, engage in a conversation, and move forward in the application process.
Conversion rates tell the story. Cold email to a purchased list might yield a 0.1 percent to 0.5 percent response rate, with very few qualified applications. Real-time, verified mortgage leads often convert at 5 percent to 15 percent or higher, depending on the product and the lender's follow-up speed. When you factor in the time saved and the reduced compliance risk, real-time leads deliver a far better return on investment.
Compliance Risks of Cold Emailing a Purchased List
The compliance landscape for mortgage marketing is unforgiving. Sending commercial email to a purchased list without clear consent can violate the CAN-SPAM Act, which requires accurate header information, a clear opt-out mechanism, and honest subject lines. But CAN-SPAM is just the starting point. The TCPA imposes strict consent requirements for calls and texts, and many email lists include phone numbers that you might be tempted to dial. If those numbers are on the National Do Not Call Registry or lack prior express written consent, you face potential fines of $500 to $1,500 per violation.
State laws add another layer. California, Colorado, and other states have enacted comprehensive privacy regulations that require notice, consent, and data subject rights. If a consumer on your purchased list resides in one of these states, your cold email could trigger a complaint and an investigation. The legal fees and reputational damage from a single enforcement action can easily exceed the entire cost of a year's worth of real-time leads.
Real-time lead platforms mitigate these risks by handling consent and verification upfront. When you buy a lead from MortgageLeads.com, you receive documentation that the consumer requested contact. The platform's terms and processes are designed to align with industry regulations, giving you a defensible position if a question arises. You still need to follow best practices in your own outreach, but the foundation is solid.
When an Email List Might Complement Your Lead Strategy
This is not to say that email lists have zero value. In specific, narrow scenarios, a well-constructed list can complement a real-time lead strategy. For example, if you have an existing database of past clients and prospects who have opted in to receive market updates, that list is a legitimate asset. Sending them a monthly newsletter with rate trends or home equity tips keeps you top of mind and can generate repeat business. The key difference is that these contacts know you and have agreed to hear from you.
Another legitimate use is a lookalike or enrichment strategy. You might use a purchased list to identify geographic areas or demographic segments that are responding, then target those areas with real-time lead purchases. But even here, you should not email the purchased contacts directly. Instead, use the list for market research and then invest in compliant lead sources for outreach.
For most mortgage brokers, the smart play is to treat email as a nurture channel for consented contacts and rely on real-time leads for new customer acquisition. This hybrid approach maximizes efficiency while minimizing risk. If you are exploring specific niche products, such as FHA loans in certain markets, you can find targeted real-time leads that match your geographic and demographic criteria. For a deeper dive into niche strategies, see our guide on Austin FHA mortgage leads, which illustrates how intent-verified leads outperform cold outreach.
How to Evaluate Real-Time Lead Providers
Not all real-time lead providers are created equal. When you evaluate a platform, look for transparency around lead sources, verification methods, and pricing. Ask how the provider generates leads: do they use search engine marketing, social media, or direct partnerships? Are leads verified by phone or just by form fill? What is the return policy if a lead is invalid? These questions separate serious providers from resellers.
MortgageLeads.com offers a range of lead types, including refinance, new purchase, home equity, and reverse mortgage leads. You can filter by geography and demographics to match your lending footprint. The platform supports multiple delivery methods, including real-time email, CRM integration, and live transfers. Live transfers are particularly valuable because you are connected directly to a consumer who is expecting your call, with a 90-second buffer to prepare.
Pricing varies by lead type and exclusivity. Exclusive leads, sold only to you, cost more but offer higher conversion potential. Shared leads cost less but require faster follow-up to beat competitors. MortgageLeads.com also operates a lead exchange where you can buy and sell leads, giving you flexibility as your business grows. For home improvement professionals seeking to expand their service offerings, platforms like HomeRemodelingLeads connect contractors with high-intent homeowners, demonstrating the value of real-time, intent-verified leads across industries.
Building a Balanced Lead Acquisition Plan
The most successful mortgage professionals do not rely on a single lead source. They build a balanced plan that includes real-time leads for immediate pipeline, referral networks for warm introductions, and email nurture campaigns for past clients. The mortgage brokers email list versus real time mortgage leads comparison is not about choosing one forever; it is about understanding where each fits.
Start by auditing your current lead sources. If you are spending money on cold email lists, calculate the true cost: not just the list price, but the time spent crafting emails, the low response rates, and the potential compliance exposure. Then compare that to the cost per funded loan from real-time leads. In most cases, the real-time lead channel wins on both efficiency and risk-adjusted return.
Next, invest in the infrastructure to handle real-time leads effectively. Speed-to-contact is critical, so set up notifications and a CRM that routes leads instantly to the right loan officer. Train your team on how to reference the consumer's inquiry and move quickly to a conversation. Track conversion rates by lead source so you can double down on what works.
Finally, keep your email list strategy focused on consented contacts. Build your own opt-in list through valuable content, webinars, and client events. Use that list to stay in touch with past clients and referral partners, not to cold-email strangers. This approach keeps your brand reputation clean and your compliance risk low.
The Bottom Line on Lists vs Real-Time Leads
Purchased email lists promise volume at a low price, but they deliver poor intent, weak contact rates, and significant compliance risk. Real-time mortgage leads cost more per contact, but they connect you with consumers who are actively seeking help and have consented to be contacted. For mortgage brokers who want a predictable pipeline and a defensible marketing operation, real-time leads are the clear choice.
If you are ready to move beyond cold lists, explore the lead types and filters available through MortgageLeads.com. Whether you need refinance leads, home equity leads, or reverse mortgage leads, the platform can match you with high-intent consumers in your market. Combine that with a thoughtful nurture strategy for your existing database, and you will build a lead engine that fuels sustainable growth.