Mortgage CRM Integration Benefits for Loan Officers
Mortgage CRM integration benefits include faster response and cleaner pipelines. Call 5106637016 to connect your lead flow today.
By Magnus Wildern
Mortgage leads move fast, and the professionals who win are the ones who respond first with context. A lead that arrives in your inbox and then sits for an hour is worth a fraction of the same lead delivered straight into your pipeline with a name, a scenario, and a timestamp attached. That gap between lead delivery and first contact is exactly where mortgage CRM integration benefits live, and it is why so many loan officers, brokers, and lending teams are rethinking how their CRM and their lead sources talk to each other.
MortgageLeads.com sits at the center of that conversation. As a B2B lead generation service and lead exchange platform, it delivers verified, real-time leads for refinance, new purchase, home equity, reverse mortgage, and home seller scenarios, and it supports API integration with third-party quoting engines and CRMs. When that flow connects to a well-configured CRM, the result is a faster, cleaner, more measurable pipeline. This article breaks down what those integrations actually do, where the value shows up on a balance sheet, and how to implement them without breaking your existing workflow.
What Mortgage CRM Integration Actually Means
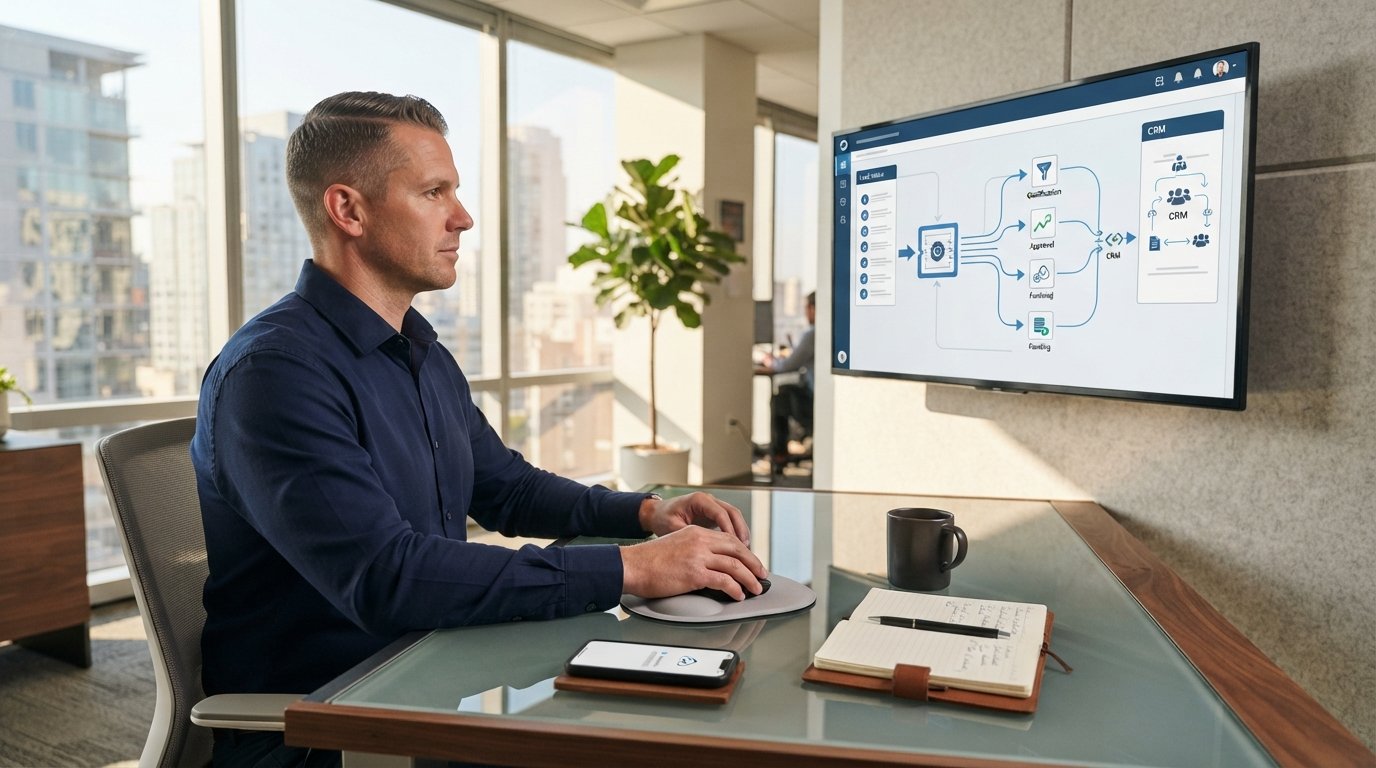
At its simplest, a mortgage CRM integration is a connector that moves lead data from a source (a lead provider, a website form, a live transfer platform) into your customer relationship management system automatically, without a human retyping anything. That sounds modest, but the mechanics matter. A proper integration maps fields, applies tags or stages, triggers notifications, and often kicks off the first touch in a nurture sequence before a loan officer has even opened the record.
The reason this matters in the mortgage industry specifically is that mortgage leads are time-sensitive and scenario-dependent. A refinance inquiry from a homeowner with a specific rate target is not the same as a home equity inquiry from someone exploring a renovation budget. A reverse mortgage lead carries different qualifying questions than a first-time buyer lead. When those distinctions get lost in a manual handoff, the follow-up gets generic, and generic follow-up converts poorly.
Integration solves that by preserving context. The lead arrives with its source, its product category, its geography, and its stated intent intact. Your CRM can then route it to the right loan officer, apply the right script, and trigger the right sequence. That is the foundation on which every other benefit below is built.
The Core Benefits of Connecting Your CRM to a Lead Source
The benefits of mortgage CRM integration tend to cluster around speed, consistency, and visibility. Speed matters because mortgage shoppers rarely talk to only one lender; the first credible response often wins the conversation. Consistency matters because a team of ten loan officers following ten different follow-up habits produces ten different conversion rates, and only one of them is good. Visibility matters because without clean data, you cannot tell which lead sources, scripts, or officers are actually producing funded loans.
Here is how those benefits show up in practice for a mortgage team using a platform like MortgageLeads.com:
- Instant lead delivery and routing: New inquiries land in the CRM within seconds and route to the right officer based on geography, product type, or availability.
- Automated first touch: A text, email, or call task fires immediately, so the prospect hears from you while the inquiry is still fresh.
- Clean, deduplicated records: Leads are matched against existing contacts so you do not pay for or chase duplicates.
- Product-specific workflows: Refinance, purchase, home equity, and reverse mortgage leads each follow their own stage progression and scripts.
- Source-level reporting: Every funded loan traces back to the lead source, campaign, and officer who worked it.
None of these are exotic features, but together they change the economics of a lead budget. When response time drops from hours to minutes, contact rates climb. When routing is automatic, no lead sits unassigned. When reporting is clean, you stop guessing which sources deserve more spend and which deserve to be cut.
How Integration Improves Lead Conversion Rates
Conversion rate is where mortgage CRM integration benefits become measurable. The biggest single lever is speed to lead. Industry data consistently shows that contacting a mortgage prospect within the first few minutes dramatically outperforms contacting them an hour later, and the drop-off continues from there. An integration that triggers an immediate call task or automated text removes the human delay that kills so many otherwise good leads.
The second lever is personalization at scale. Because integrated leads arrive with product and scenario data attached, your CRM can send a refinance prospect a message about rate-and-term options and a home equity prospect a message about accessing equity without refinancing. That relevance raises reply rates and makes the first conversation warmer.
The third lever is follow-up discipline. Most mortgage leads do not convert on the first touch. They convert on the fourth, fifth, or tenth touch over weeks or months. A CRM with an integrated lead flow can run multi-channel nurture sequences automatically, so no lead falls through the cracks just because a loan officer got busy. If you want a deeper look at how lead quality and follow-up interact at the local level, our guide on generating quality Springfield mortgage leads walks through the same principles in a specific market.
Exclusive vs. Shared Leads and What Integration Changes
Lead type affects how you should configure your CRM. Exclusive leads, sold once, justify aggressive, high-touch sequences because you are the only one calling. Shared leads, sold to multiple buyers, demand even faster response and often a different script that acknowledges the prospect may be hearing from several lenders. Live transfers, where the prospect is connected to you on a call, need almost no automation beyond immediate logging and disposition tracking.
A well-built integration lets you tag leads by type and apply the right workflow automatically. That prevents the common mistake of running a slow, educational nurture sequence on a shared lead that needed a phone call in the first sixty seconds.
Operational Efficiency: Less Admin, More Selling
Loan officers are not paid to copy and paste. Yet in teams without integration, that is exactly what happens: leads arrive by email or portal, get manually entered into the CRM, get manually assigned, and get manually followed up. Every one of those steps is a place where time leaks and errors creep in.
Integration collapses those steps. Data flows in once, cleanly, and the CRM handles assignment and task creation. For a team processing hundreds of leads a month, the recovered hours are substantial, and those hours go back into conversations with borrowers. That is one of the quieter but most durable mortgage CRM integration benefits: it does not just improve conversion, it improves capacity.
There is also a compliance dimension. Mortgage communication is regulated, and having a system of record that logs every call, text, and email in one place makes audits and internal reviews far less painful. When leads enter the CRM automatically, the record is complete from the first moment of contact.
Better Data, Better Decisions
Integration turns your CRM into a reporting engine. Because every lead carries its source, product type, and outcome, you can answer questions that are nearly impossible to answer with manual tracking:
- Which lead sources produce the highest funded-loan rate per dollar spent?
- Which loan officers convert which product types best?
- How long does it take, on average, from lead arrival to first contact, and how does that correlate with conversion?
- Which nurture sequences actually move prospects to application?
With those answers, lead buying becomes strategic rather than reactive. You can shift budget toward the sources and products that work, set buying caps intelligently, and coach officers with real data instead of impressions. Platforms that support API integration, like MortgageLeads.com, make this easier because lead data arrives in structured fields rather than free-text emails.
Choosing a Lead Partner That Supports Integration
Not every lead provider supports clean CRM integration. Some deliver leads by CSV download, some by email, and some through portals that require manual export. Those methods can work at low volume, but they undercut nearly all the benefits described above. When evaluating a lead source, ask directly whether it offers API integration, what fields it passes, and whether it supports real-time delivery.
MortgageLeads.com was built for exactly this use case. It operates as a B2B lead generation service and lead exchange platform, sourcing consumer inquiries through digital channels and verifying them for mortgage-specific intent before distribution. Leads can be filtered by geographic and demographic criteria, delivered as exclusive, shared, or live transfers, and pushed into third-party quoting engines and CRMs via API. The platform has been operating in financial lead generation for over 13 years and runs on a proprietary cloud-based lead exchange.
It is worth noting what MortgageLeads.com is not: it is not a lender, broker, or loan originator, and it does not quote rates or approve loans. Its role is to connect mortgage professionals with high-intent consumers, and the CRM integration is what makes that connection operationally useful. Teams that also work in adjacent verticals sometimes ask about cross-industry data sources; for those exploring insurance-side lead flow, resources like BestInsuranceLeads illustrate how verified, high-intent consumer data is structured in a neighboring market.
Implementation Steps for a Smooth Integration
Getting integration right is less about technology and more about planning. The teams that struggle usually skip the mapping and workflow design steps and then wonder why leads arrive in the wrong stage or get assigned to the wrong person. A disciplined rollout avoids most of that.
Here is a practical sequence that works for most mortgage teams:
- Audit your CRM fields and stages. Know what data you can store and how your pipeline is structured before you connect anything.
- Map lead fields to CRM fields. Decide where product type, geography, source, and intent data will live.
- Define routing rules. Assign leads by geography, product specialty, license, or round-robin, and document the logic.
- Build the first-touch sequence. Decide what happens in the first five minutes, the first day, and the first week after a lead arrives.
- Test with a small batch. Run a limited volume through the integration, verify data accuracy, and fix issues before scaling.
- Review and refine monthly. Use source-level reporting to adjust routing, scripts, and budget.
Most integrations can be live within a week or two if the CRM supports standard API connections. The bigger investment is usually in defining the workflows, and that investment pays off because it forces your team to agree on how leads should be handled.
Common Mistakes That Undermine Integration
The most common mistake is treating integration as a one-time setup. Lead sources change, products evolve, and team composition shifts. Routing rules that made sense six months ago may be sending refinance leads to an officer who now focuses on purchase. Schedule a quarterly review of your integration logic the same way you review your budget.
The second mistake is over-automating the first touch. Automation is excellent for speed, but mortgage borrowers still want a human on the other end. Use automation to trigger contact and log activity, not to replace the conversation. The third mistake is ignoring data hygiene. Duplicates, stale records, and inconsistent tags will corrupt your reporting and erode trust in the system. Deduplication and field validation should be part of the integration design, not an afterthought.
Finally, do not integrate in isolation. Your CRM, your lead source, and your quoting tools should all agree on the same data definitions. When they do, the pipeline becomes a single source of truth rather than three systems that disagree.
The Bottom Line on Integration Value
Mortgage CRM integration benefits compound. Faster response raises contact rates. Better routing raises accountability. Cleaner data raises the quality of every decision you make about budget, scripts, and staffing. Individually, each improvement looks incremental; together, they change how much revenue a given lead budget produces.
For mortgage professionals evaluating lead sources, the practical takeaway is simple: prioritize providers that support real-time API delivery and structured data, then invest the time to configure your CRM to use that data well. MortgageLeads.com is built around that model, with verified leads across refinance, purchase, home equity, reverse mortgage, and home seller categories, plus the integration support needed to move them straight into your workflow. Connect the systems, define the rules, and let the pipeline do more of the work.