Mortgage Lead Distribution Models Compared for Lenders
Compare mortgage lead distribution models for lenders, from round-robin to weighted and geographic routing. Call (510)-663-7016 to optimize your lead flow.
By Lyra Ashbourne
Every purchased mortgage lead carries a hidden cost that rarely appears on the invoice: the cost of routing it to the wrong person, at the wrong time, with the wrong context. Lenders spend heavily to acquire high-intent consumer inquiries, yet the difference between a 4 percent and a 12 percent contact rate often comes down to distribution logic, not lead quality. When a refinance inquiry sits in a shared inbox for 40 minutes while three loan officers assume someone else claimed it, the lead has effectively been wasted before the first dial. Understanding how distribution models work, and where each one breaks down, is one of the highest-leverage operational decisions a mortgage team can make.
The stakes are higher than most teams realize. Consumer expectations for speed have compressed dramatically, and the first professional to make meaningful contact usually wins the relationship. That means the routing layer sitting between a lead source and your loan officers is not administrative plumbing. It is the conversion engine. This guide compares the major mortgage lead distribution models available to lenders, explains how each interacts with lead type and specialization, and highlights the mistakes that quietly suppress contact rates across teams of every size.
Why Distribution Logic Decides Lead ROI
A lead is not a static asset. It is a perishable signal of intent. A homeowner who requests refinance information at 9 a.m. on a Tuesday is in a very different psychological state by 2 p.m. the same day. Distribution models exist to minimize that decay by moving the lead to a capable human as fast as possible. When teams evaluate mortgage lead distribution models compared for lenders, they are really evaluating how quickly and intelligently a lead reaches the person most likely to convert it.
Poor distribution creates three invisible losses. First, speed-to-lead suffers: leads queue behind manual assignment or sit unclaimed in shared pools. Second, fit suffers: a reverse mortgage inquiry routed to a loan officer who only works purchase loans gets a polite but ineffective call. Third, accountability suffers: when multiple people can claim the same lead, everyone assumes someone else already did. Each of these losses compounds across hundreds of leads per month, and none of them show up in a lead source report.
Strong distribution does the opposite. It enforces speed through automation, enforces fit through rules tied to loan officer specialization, and enforces accountability through clear ownership at the moment of delivery. Before comparing specific models, it helps to establish the criteria that matter most: time to first contact, match quality between lead and loan officer, fairness and morale across the team, and the administrative overhead required to keep the system running.
Round-Robin Routing: Simplicity and Its Limits
Round-robin distribution assigns each incoming lead to the next loan officer in a rotating sequence. Lead one goes to Alex, lead two to Jordan, lead three to Priya, and the cycle repeats. It is the easiest model to implement, requires almost no configuration, and has an intuitive fairness story: over time, everyone receives roughly the same volume.
The model works best for teams with relatively uniform skill sets and a single dominant lead type. If every loan officer on the team handles conventional purchase loans equally well, round-robin keeps morale high and disputes low. The simplicity is genuine: no rules engine, no weighting debates, no geographic mapping.
The limits appear quickly, however, as teams grow or specialize. Round-robin ignores fit entirely. A high-value jumbo inquiry might land on the newest hire while a seasoned jumbo specialist receives a first-time buyer lead they will convert at a lower rate. It also ignores availability. A loan officer on vacation, in a closing, or out sick still receives their turn, and the lead waits. Many teams patch this with manual pause toggles, but toggles depend on humans remembering to use them, and humans do not always remember.
Round-robin also interacts poorly with lead type diversity. If a team buys refinance, home equity, and reverse mortgage leads from a single source, strict rotation will push each type to whoever is next in line rather than whoever is licensed, trained, or motivated to work it. For small, homogeneous teams, round-robin remains a reasonable default. For anyone buying multiple lead categories, it is usually a starting point that needs refinement.
Weighted Distribution: Matching Volume to Performance
Weighted distribution assigns leads according to configurable percentages rather than strict rotation. A top performer might receive 30 percent of new purchase leads, a mid-tier producer 20 percent, and newer officers smaller shares. Weights can reflect conversion history, license coverage, work capacity, or contractual arrangements with the lead source.
The appeal is obvious: more leads flow to the people most likely to convert them, which raises overall team ROI. Weighted models also give managers a lever for coaching and incentives. A loan officer who improves their contact rate can be rewarded with additional volume, creating a visible performance culture. For teams buying expensive live transfers, where each connection carries a meaningful per-lead cost, directing volume toward proven closers can be the difference between a profitable channel and an unprofitable one.
Weighting introduces its own risks. Weights based on stale performance data punish loan officers who have improved or who serve markets that shifted. Opaque weights damage morale: if team members cannot see why one person receives more leads, they assume favoritism. And weights require maintenance. A model configured in January and never revisited by June is likely misallocating volume.
The healthiest weighted programs share two traits. First, the criteria are transparent and communicated: conversion rate over a trailing period, license coverage, availability windows, or a documented combination. Second, weights are reviewed on a fixed cadence, monthly or quarterly, using real performance data. Weighted distribution is powerful precisely because it is tunable, and that power only pays off when someone actually tunes it.
Geographic Routing: Local Expertise as a Conversion Advantage
Geographic routing sends leads to loan officers based on territory: ZIP code, county, metro area, or state. The logic is that local knowledge converts better. A loan officer who knows which neighborhoods have HOA quirks, which counties have slower appraisal turnarounds, and which local assistance programs exist can speak with more authority than a generalist reading from a script.
Geography matters more than many teams assume. Purchase leads in particular often involve local market questions, and borrowers respond well to professionals who clearly operate in their area. For lenders buying leads filtered by geography, which is a standard capability on platforms like MortgageLeads.com, geographic routing aligns the delivery rule with the lead filter that generated the inquiry in the first place.
The model has predictable failure modes. Coverage gaps are the biggest: what happens to a lead from a ZIP code no one owns? Teams need fallback rules, such as routing uncovered areas to a designated overflow officer or into a round-robin pool. Imbalance is the second issue. Dense metro territories generate far more volume than rural ones, so pure geographic routing can leave some officers overwhelmed and others underutilized. Many teams solve this by combining geography with weighting, so territory defines eligibility while weights define share within it.
A third consideration is licensing. Geographic routing is only valid if the assigned officer is licensed in that state. For multi-state lenders, the routing rule must check license coverage before assignment, or the lead lands with someone who legally cannot work it. This is a configuration detail that is easy to miss and expensive to discover after the fact.
How Distribution Rules Interact With Lead Type and Specialization
The most common distribution mistake is choosing a single model for all lead types. Refinance, new purchase, home equity, reverse mortgage, and home seller leads behave differently, and the routing logic should reflect that. A model that is optimal for shared home equity leads at modest per-lead cost is rarely optimal for expensive live transfers.
Consider how the requirements differ by category. Refinance leads reward speed and rate expertise, and they often arrive in volume, making automated real-time delivery essential. New purchase leads benefit from local knowledge and Realtor relationships, which favors geographic rules. Home equity leads are frequently lower-cost and higher-volume, so broad distribution with fast follow-up works well. Reverse mortgage leads require specialized licensing and a consultative approach, meaning they should route only to officers trained and licensed in that product, regardless of rotation fairness.
A practical framework many teams adopt layers rules in sequence:
- Product eligibility: filter to officers licensed and trained for the lead type (for example, reverse mortgage or state-specific licensing).
- Geographic eligibility: narrow to officers covering the lead's territory, with a defined overflow path for gaps.
- Availability check: exclude officers who are offline, at capacity, or in a paused state.
- Weighted or round-robin assignment: distribute within the eligible pool using performance weights or rotation.
- Escalation timer: if the lead is not claimed within a set window, reassign automatically.
This layered approach preserves the fairness benefits of rotation while respecting the fit requirements that drive conversion. It also scales: as the team adds products or territories, new eligibility rules slot into the sequence without redesigning the whole system. Teams that buy leads for specialized products, such as the HELOC strategies covered in this guide to generating Raleigh HELOC leads for lenders, can route those inquiries only to officers equipped to work them.
API Delivery: Routing Leads Into Your Systems in Real Time
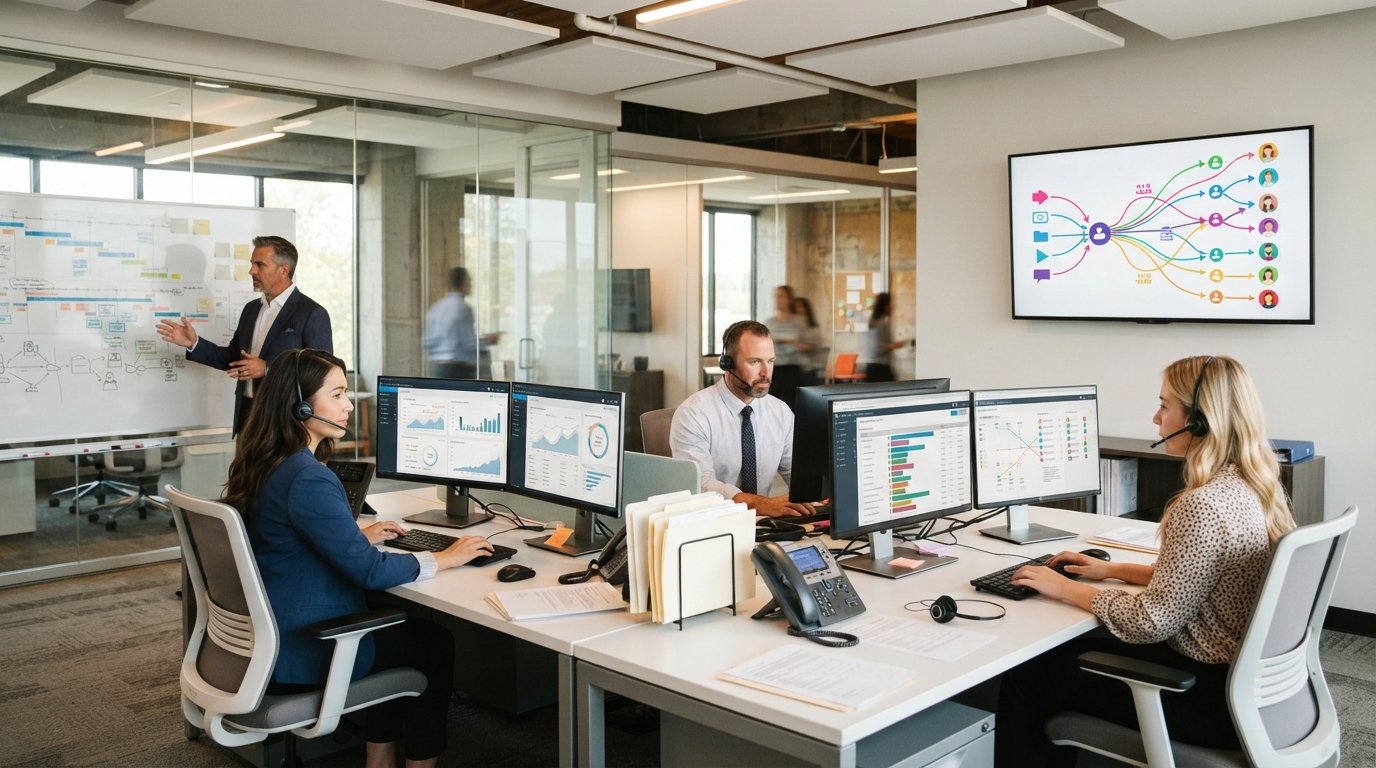
Distribution quality is capped by delivery speed. If leads arrive by email digest or CSV download, even the best routing rules operate on stale data. API delivery changes the equation by pushing leads into your CRM, LOS, or routing engine the moment they are generated, where automated rules can assign them in seconds rather than minutes.
Real-time API delivery enables capabilities that manual workflows cannot match. Assignment can happen instantly based on the layered rules described above. Duplicate checks can run before the lead reaches a loan officer's queue. Round-robin state can persist in your own system rather than in a spreadsheet. And escalation timers can trigger automatically when a lead goes unclaimed, reassigning it without a manager intervening.
Platforms built for this workflow, including MortgageLeads.com, support API integration with third-party quoting engines and CRMs, which means routing logic can live in the system your team already uses. The practical benefit is continuity: lead data, assignment history, and contact outcomes stay in one place, making it far easier to audit which distribution rules actually produce conversations. When evaluating any lead source, ask whether delivery is real-time and whether the integration is a true API rather than a scheduled export. The answer determines whether your routing rules run on live signals or yesterday's news.
Speed also shapes consumer experience. Live transfer leads, where a consumer is connected by phone within a short buffer window, depend entirely on real-time routing to the right officer. If the transfer lands with someone unavailable or unqualified, the connection is lost and the spend is wasted. API-driven routing is what makes live transfers operationally viable at scale.
Common Distribution Mistakes That Suppress Contact Rates
Most contact-rate problems trace back to a small set of recurring distribution errors. The first is manual assignment. When a manager or coordinator hand-assigns leads, every lead waits for human attention, and the wait is longest exactly when volume is highest. The second is the shared-pool free-for-all, where multiple officers can claim the same lead and everyone hesitates, assuming someone else is dialing. Ambiguous ownership is the enemy of speed.
The third mistake is ignoring availability. Routing rules that do not account for shifts, time zones, vacations, or capacity will deliver leads to people who cannot answer them. The fourth is static configuration: rules set once and never reviewed drift out of alignment with actual performance and staffing. The fifth is missing escalation. Without a claim timer and reassignment path, unclaimed leads simply decay in someone's queue.
There is also a subtler error: routing by lead source rather than lead content. Teams sometimes assign all leads from a given vendor to one officer, which conflates source quality with individual fit. Routing should respond to what the lead actually is (product, geography, intent) rather than which campaign produced it. Finally, teams frequently skip measurement. If you cannot report time-to-first-contact and contact rate by routing rule, you cannot know which model is working. Instrument the pipeline before optimizing it.
One more consideration deserves attention: adjacent lead categories. Some lenders and their marketing partners also work home improvement or insurance inquiries, and the same routing discipline applies there. If your operation touches those categories, resources such as HomeRemodelingLeads illustrate how high-intent consumer inquiries in adjacent verticals are sourced and delivered, which can inform how you think about verification and speed across all your lead channels.
Choosing and Tuning a Model for Your Team
There is no universally correct distribution model. The right choice depends on team size, product mix, licensing footprint, and lead volume. A three-person team buying one lead type should start with round-robin plus an availability toggle and an escalation timer. A twenty-person multi-state team buying several products needs layered eligibility rules with weighted assignment inside each eligible pool. A team buying live transfers should prioritize API delivery and real-time assignment above all else, because the transfer window leaves no room for queuing.
Whatever model you choose, treat distribution as a living system. Review routing performance monthly using concrete metrics: time to first contact, contact rate by rule and by officer, and conversion by lead type. Adjust weights, territories, and escalation windows based on what the data shows. Communicate rule changes to the team so fairness remains visible. And revisit the configuration whenever you add a product, a state, or a lead source, because each addition changes the eligible pool and therefore the optimal rules.
Lenders who treat distribution as a first-class operational function consistently outperform those who treat it as an afterthought. The leads may come from the same sources at the same prices, but the team that routes them intelligently, delivers them in real time, and measures the results will contact more consumers, book more applications, and close more loans from the same spend. Start with the layered framework, instrument your pipeline, and let the contact-rate data guide every adjustment.