Mortgage Lead Distribution Platform Features for Multi Office Lenders
Discover the mortgage lead distribution platform features for multi office lenders that drive fairness and conversion. Call (510)-663-7016 to learn more.
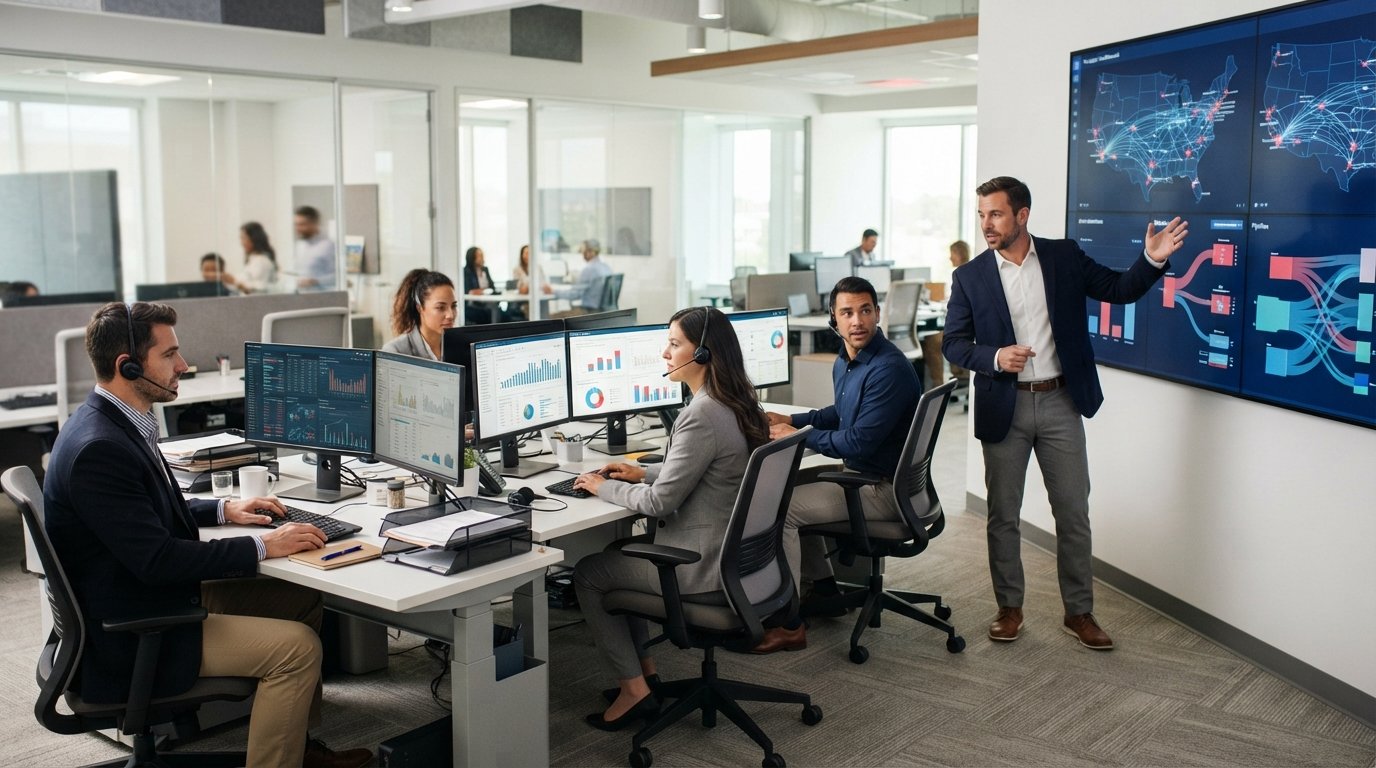
Running a multi office lending operation means every branch, every loan officer, and every support staff member needs the right borrower at the right time. When a refinance inquiry lands in the wrong office or a purchase lead sits untouched because the nearest branch never saw it, you lose the loan and the relationship. A mortgage lead distribution platform built for multi office lenders solves that routing problem, but only if it includes the specific features your branch network actually needs. This article breaks down the capabilities that matter most, from intelligent routing rules to fairness controls, reporting visibility, and API integrations that keep each office running on its own CRM.
Routing Rules That Send Purchase and Refinance Leads to the Right Branch
The first job of any distribution platform is to get each lead to the person most likely to close it. For multi office lenders, that means routing based on product type, geography, license coverage, and loan officer availability. A new purchase lead and a refinance lead rarely belong in the same queue, and a borrower in one state should never land on the desk of a loan officer who cannot lend there.
Strong platforms let administrators build routing rules that combine multiple conditions. You might route a purchase inquiry to the branch closest to the property address while sending a refinance inquiry to the office with the highest refi conversion rate. You can also set capacity limits so a high performer does not receive more leads than they can work, and time-based rules that shift leads to another office when a branch is closed. These rules should be editable without developer support, because branch networks change, loan officers move, and licensing coverage shifts.
Consider how routing affects the borrower experience. A purchase lead expects a call within minutes, not hours. If your routing logic sends a lead to a branch that is slower to respond, conversion drops. The best platforms include fallback routing: if the assigned loan officer does not accept or contact the lead within a set window, the lead automatically moves to the next qualified recipient. That single feature prevents the most common source of wasted spend in multi office environments.
For lenders buying leads from an exchange, routing should also respect lead type. Exclusive leads can be assigned to a single loan officer, while shared leads may need to go to a team queue where multiple agents can work them. The platform should make that distinction clear at the point of distribution so no one assumes they have exclusivity when they do not.
Fairness Controls That Prevent Lead Cherry Picking Across Offices
Multi office lenders face a political and operational challenge that single office shops never see: fairness. If one branch manager has a close relationship with the distribution administrator, or if one office consistently grabs the easiest leads, other branches will disengage. Over time, the underfed offices stop working the leads, and your overall conversion rate falls even though total lead volume has not changed.
Fairness controls solve this by enforcing distribution rules that no one can override casually. Common features include round robin assignment, weighted distribution based on branch size or performance, and caps that limit how many leads an office or individual can receive per day or week. The platform should log every assignment and every manual reassignment so administrators can audit whether the rules are being followed.
Another critical control is lead visibility. Some platforms allow all offices to see all leads, which encourages cherry picking: the fastest office grabs the best leads, and slower offices get the leftovers. A better approach restricts visibility so each office sees only the leads routed to it, with administrators retaining full visibility for oversight. If your network is large enough to need a shared pool, the platform should at least enforce a claim window that gives every eligible office a fair chance to respond before the lead moves on.
Fairness also applies to lead quality. If one office consistently receives older or lower intent leads, the platform should surface that imbalance in reporting. Administrators can then adjust routing weights or investigate whether a particular lead source is underperforming. Without that visibility, fairness becomes a matter of trust, and trust erodes quickly when commissions are on the line.
Reporting and Visibility for Branch Managers Tracking Lead to Funding
Branch managers need to know what happened to every lead, not just how many they received. A distribution platform that stops at delivery leaves managers guessing about contact rates, application rates, and funded loans. For multi office lenders, reporting should connect the lead source to the loan outcome so each branch can see its true return on lead spend.
At a minimum, the platform should provide dashboards that show leads received, leads contacted, applications started, and loans funded, broken down by office, loan officer, lead type, and time period. Managers should be able to see how quickly their team responds to new leads and where leads stall in the pipeline. If a branch has a high contact rate but a low application rate, that points to a training issue. If a branch has a low contact rate, the problem may be staffing or routing.
Reporting should also support comparison across offices. A district manager overseeing five branches needs to see which offices are converting at the highest rate and which are falling behind, with the ability to drill into individual loan officer performance. Exportable reports help with compensation planning and with justifying lead spend to ownership. The platform should make it easy to schedule recurring reports so managers receive them without logging in every day.
One subtle but important feature is attribution. When a lead is transferred between offices, or when a loan officer leaves and their pipeline is reassigned, the platform should preserve the original source and assignment history. Without that trail, managers cannot accurately credit the office that generated the opportunity, and disputes become common. Look for platforms that maintain a full audit log of lead movement and status changes.
For lenders who also sell leads or participate in a lead exchange, reporting should extend to inbound and outbound lead flow. You want to see which offices are buying leads, which are selling, and how those transactions affect overall performance. This is especially relevant if your network includes both retail and wholesale channels.
API Options for Pushing Distributed Leads Into Branch Level CRMs
No two branches run their pipelines the same way. One office may use a national CRM, another may rely on a legacy system, and a third may have a custom-built tool. A distribution platform that only supports a single CRM creates friction: leads arrive in one system and must be manually re-entered into another, which slows response time and introduces errors.
API integration solves this by pushing distributed leads directly into each branch's system of record. The platform should offer a documented API that supports real-time lead delivery, status updates, and field mapping. Administrators should be able to configure which fields are sent to which branch, and how leads are formatted for each CRM. For example, a branch using a modern CRM might receive leads via a webhook with JSON payloads, while a branch on an older system might receive leads via a scheduled file transfer.
The API should also support two-way communication. When a loan officer updates a lead status in their CRM, that update should flow back to the distribution platform so reporting stays accurate. Without two-way sync, managers end up reconciling two systems manually, which defeats the purpose of the platform. Look for APIs that support status callbacks, lead returns, and duplicate detection.
Security matters here as well. The API should use industry-standard authentication, encrypt data in transit, and allow administrators to scope access by branch or role. You do not want a branch-level integration to have visibility into every lead in the network. Role-based access controls should extend to API credentials so each branch's integration only sees its own data.
If your network includes offices that are not ready for a full API integration, the platform should offer alternatives such as email parsing, CSV imports, or direct login access. The goal is to meet each branch where it is while keeping distribution centralized.
For lenders exploring how lead distribution fits into a broader acquisition strategy, it helps to understand the consequences of poor distribution. Sending the same lead to multiple agents without clear rules can damage borrower trust and waste budget, as we explain in our guide on sending leads to multiple agents. A platform with strong routing and fairness controls avoids those pitfalls.
Scalability and Compliance Features Multi Office Lenders Should Demand
As your branch network grows, the distribution platform must grow with it. Scalability is not just about handling more leads; it is about handling more offices, more users, more lead types, and more complex routing rules without degrading performance. A platform that works well for five offices may struggle at fifty if it lacks the right architecture.
Compliance is the other non-negotiable. Mortgage lending is heavily regulated, and lead distribution touches several rules at once: consent to contact, do-not-call requirements, state licensing, and data privacy. The platform should capture and store consent language for each lead, respect opt-outs across the entire network, and prevent leads from being routed to loan officers who are not licensed in the borrower's state. Audit logs should be immutable so you can demonstrate compliance during an exam.
Here are the scalability and compliance features to prioritize:
- Role-based access controls that separate branch-level visibility from network-wide administration
- Consent and opt-out tracking that applies across all offices and lead sources
- Licensing filters that block routing to unlicensed loan officers automatically
- Immutable audit logs for lead assignment, status changes, and user actions
- Configurable data retention policies that align with state and federal requirements
These features protect the institution as a whole, not just individual branches. A compliance failure in one office can create liability for the entire network, so centralized controls are essential. The platform should also support periodic access reviews so administrators can confirm that departed employees no longer have access to lead data.
Beyond compliance, look for platforms that support multi office hierarchies. You may have regional managers, branch managers, and team leads, each needing a different view of the data. The platform should mirror your organizational structure so permissions and reporting align with how you actually run the business. Flat user models force workarounds that undermine both fairness and accountability.
Finally, consider vendor stability and support. A distribution platform becomes deeply embedded in your operations, so you need a provider with a track record in financial lead generation. MortgageLeads.com, for example, has operated in the space for over a decade and offers a proprietary cloud-based exchange with API integration for third-party CRMs and quoting engines. The platform supports exclusive, shared, and live transfer leads, which gives multi office lenders flexibility in how they distribute different lead types across branches. Lenders evaluating legal or professional service lead partners can also review resources like AttorneyLeads to see how similar distribution models work in adjacent industries.
Evaluating Platforms: Questions to Ask Before You Commit
Before selecting a distribution platform, run a structured evaluation. Start by mapping your current branch structure and lead flow, then compare each vendor against your actual needs rather than a generic feature list. The right platform should reduce manual work for administrators, improve response time for loan officers, and give managers the reporting they need to make decisions.
Ask vendors these questions:
- Can routing rules combine product type, geography, licensing, and capacity without custom development?
- How does the platform enforce fairness across offices, and can administrators audit manual reassignments?
- What reporting is available for branch managers, and can it connect lead source to funded loan?
- Does the API support two-way sync with branch-level CRMs, and how are credentials scoped?
- How does the platform handle consent, opt-outs, and licensing compliance across the network?
After the demo, ask for references from lenders with a similar number of offices. A platform that works for a single large call center may not work for a distributed branch network, and vice versa. Test the routing logic with real scenarios from your business, such as a purchase lead near a branch boundary or a refinance lead from a state where only one office is licensed. The platform's behavior in those edge cases tells you more than any feature checklist.
Also consider implementation effort. Moving from a manual or homegrown process to a formal platform requires data migration, user training, and process changes. Vendors should provide a clear onboarding plan and dedicated support during the transition. If a vendor cannot explain how they will get your branches live within a reasonable timeframe, that is a warning sign.
Pricing deserves scrutiny as well. Some platforms charge per lead, some charge per user, and some charge a flat platform fee. Understand how costs scale as you add offices and lead volume. A low upfront price can become expensive at scale if per-lead fees are high, and a flat fee can be a bargain if you distribute a large volume. Model your expected volume over twelve months before signing.
Finally, think about the long term. Your branch network will change, your lead sources will evolve, and your CRM stack may shift. The platform should be flexible enough to accommodate those changes without a full replatforming. That means configurable routing, open APIs, and a vendor that releases meaningful updates on a regular cadence. A platform that meets your needs today but cannot adapt tomorrow will become a bottleneck within a few years.
Choosing the right mortgage lead distribution platform features for multi office lenders comes down to routing precision, fairness enforcement, reporting depth, and integration flexibility. Get those four right, and your branches will spend less time fighting over leads and more time closing them. Start by documenting your current distribution process, then evaluate platforms against the scenarios that matter most to your network. The effort upfront pays off in higher conversion rates, better branch accountability, and a borrower experience that feels fast and personal no matter which office answers the call.