Mortgage Lead Exchange: Independent Agents vs Loan Officers
Compare mortgage lead exchange for independent agents versus loan officers, from licensing scope to caps. Call (510)-663-7016 for guidance.
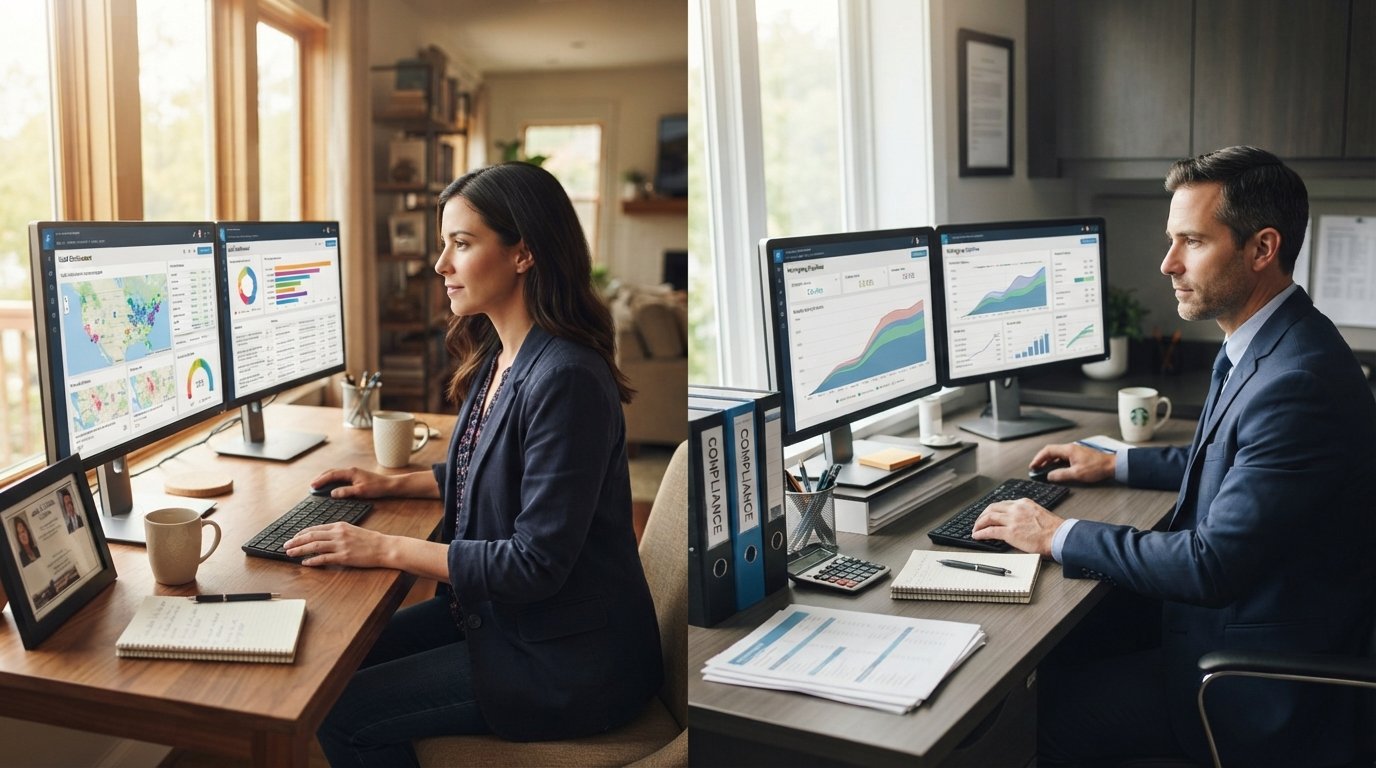
Two mortgage professionals can log into the same lead exchange on the same morning, buy from the same pool, and walk away with completely different results. The difference is rarely effort. It is role design. An independent agent and a loan officer operate under different licensing scopes, different compliance obligations, and different conversion economics. Treating a lead exchange as one-size-fits-all is how good producers end up with bad pipelines.
This breakdown of mortgage lead exchange for independent agents versus loan officers covers what each role can legally work, which filters and exclusivity settings make sense, how volume caps and returns should be set, and how the two roles can cooperate instead of competing over the same consumer. If you buy leads, the goal is simple: spend on the segment your license and workflow can actually convert.
Why the Same Lead Pool Produces Different Results
A lead exchange is a marketplace. Sellers list consumer inquiries, buyers filter and purchase based on criteria, and the platform handles delivery. On the surface, everyone sees the same inventory. Underneath, the roles diverge fast. An independent agent may hold a real estate license with mortgage loan originator authority, or may work mortgage leads as a referral source. A loan officer typically works under a licensed lender or brokerage and is bound by that entity's product menu, pricing engine, and compliance review.
Those structural facts change everything downstream. A lead that is perfect for a loan officer with a full refinance menu may be useless to an agent who cannot quote a rate. A lead that suits an agent's purchase-focused referral model may waste a loan officer's time if the consumer is twelve months from applying. Role clarity is the first filter, and it costs nothing to apply.
The exchange itself is neutral. Platforms such as MortgageLeads.com distribute verified, real-time inquiries for refinance, new purchase, home equity, and reverse mortgage scenarios, filterable by geography and demographics. What the buyer does with that inventory depends on license scope, exclusivity budget, and follow-up capacity. Compare the two roles side by side before you set a single filter.
Licensing and Product Scope: What Each Role Can Actually Work
Licensing is the hard boundary. An independent agent's authority depends on state rules and on whether the agent holds a mortgage loan originator license through the Nationwide Multistate Licensing System. Some agents can originate; many cannot and instead refer consumers to a licensed lender for compensation. A loan officer almost always works under an entity license, which means the products available to the consumer come from that lender's menu, not from the officer's personal preference.
Product scope follows licensing. A loan officer at a lender with strong government lending channels can work FHA, VA, and USDA scenarios that an agent without those lender relationships cannot place. An agent with deep local purchase relationships may add value on new purchase and home seller leads even when the eventual loan closes elsewhere. Neither role is superior. They are simply built for different stages of the transaction.
Before buying anything, confirm which lead categories your license and your lender's product menu actually support:
- Refinance leads: require rate-and-term or cash-out capability and a pricing engine you can quote from.
- New purchase leads: require pre-approval capacity and realtor coordination, which favors agents with local networks.
- Home equity leads: require HELOC or second-lien products, often priced lower per lead but with tighter qualification.
- Reverse mortgage leads: require specialized certification and a lender that actually offers the product.
If a category is not on that list for your role, skip it. Buying leads you cannot legally or practically close is the fastest way to burn budget. For a deeper look at product-specific tactics, the guide on Austin FHA mortgage leads shows how lender channel strength shapes which inquiries convert.
Filter and Exclusivity Choices That Fit Each Role
Filters are where role differences become operational. An independent agent usually runs a lean operation and cannot absorb high volume, so precision beats reach. A loan officer inside a larger shop may have processing support and can work a broader funnel. The filter settings should mirror those realities.
Geography is the first lever. Agents live on local relationships, so county-level or ZIP-level targeting protects their time. Loan officers at lenders with statewide or multistate reach can widen the radius, but only if their operations can service those borrowers. Demographic filters matter too. Credit band, loan purpose, property type, and occupancy status all narrow the pool, and each filter you add raises lead quality while shrinking volume.
Exclusivity is the second lever, and it is often misunderstood. Exclusive leads are sold once, cost more, and reward fast, personalized follow-up. Shared leads are sold to multiple buyers, cost less, and reward speed and script discipline. A common split looks like this:
- Independent agents: lean toward exclusive leads in a tight geography, because their conversion depends on personal trust and they cannot win a price war.
- Loan officers: can mix shared and exclusive depending on processing capacity, using shared leads to fill the top of the funnel and exclusive leads for high-intent segments.
- Live transfers: suit loan officers with phone coverage during business hours, since the 90-second buffer and stated 100% contact rate reward immediate pickup.
Pricing and filter rules can change, so confirm current packages on the product pages before committing. The principle holds regardless: match exclusivity to your follow-up capacity, not to your ambition.
Volume, Caps, and Returns: Setting Realistic Expectations
Volume discipline separates professionals from hobbyists. A cap is a spending limit, and every buyer should set one before the first lead arrives. Independent agents typically cap lower and review weekly, because a single bad batch can dominate their month. Loan officers with team support can cap higher but should still tie the cap to contact rate and appointment rate, not to hope.
Returns are the safety valve. Most exchanges allow returns within a defined window for wrong numbers, disconnected lines, or consumers who deny requesting information. Return rates are a diagnostic, not a trophy. A high return rate signals filter misalignment or slow contact. A near-zero return rate can signal that you are not disputing bad leads at all. Track both, and review the numbers monthly against your cost per funded loan.
Expectations should be set in writing. Before buying, ask the exchange three questions: what is the return window, what qualifies as a valid return, and how are live transfers billed if the consumer cannot be reached. Then set your cap so that one bad week does not end the experiment. Volume without a cap is gambling; volume with a cap is testing.
Collaboration: Agents and Loan Officers on the Same Lead Pool
The most underused strategy in mortgage lead exchange for independent agents versus loan officers is cooperation. The two roles often chase the same consumer and never speak. That is waste. An agent who refers a purchase lead to a trusted loan officer and a loan officer who refers a home seller lead back to that agent create a loop where one purchased lead can produce two transactions.
Structure the loop with simple agreements. Define who owns the initial contact, who discloses the referral relationship, and how compensation flows under state rules. Keep the consumer experience clean: one point of contact, one clear explanation of who is doing what. When the loop works, the lead exchange becomes a shared pipeline rather than a zero-sum auction.
Adjacent home service categories can extend the loop further. A borrower preparing to list often needs repairs or upgrades first, and platforms such as home remodeling lead platforms connect contractors with high-intent homeowners, which can help agents and loan officers time their outreach around real projects instead of cold calls.
Onboarding Checklist Before You Buy
Onboarding is where most bad purchases are prevented. Run this checklist once per role, and rerun it whenever your license, lender, or product menu changes.
- Confirm your license scope and your lender's product menu in writing.
- Decide which lead categories you can actually close, and exclude the rest.
- Set geography and demographic filters that match your service area and capacity.
- Choose exclusivity and delivery format (form, pay-per-call, or live transfer) based on follow-up staffing.
- Set a spending cap and a weekly review date before the first lead arrives.
- Read the return policy and write down the dispute process.
- Test API or CRM integration so leads land in your workflow without manual entry.
Each step takes minutes and prevents expensive mistakes. The licensing and product confirmation alone eliminates the most common source of wasted spend. The cap and review date keep the experiment honest. The integration step matters more than buyers expect, because a lead that sits in an inbox for an hour is already cold.
Mortgage lead exchange for independent agents versus loan officers is not a contest. It is a matching problem. Agents win with precision, exclusivity, and local trust. Loan officers win with product breadth, phone coverage, and processing capacity. Buy within your role, cap your risk, dispute bad leads, and build referral loops with the other side of the transaction. Do that, and the same lead pool that frustrates unprepared buyers becomes a predictable source of funded loans.