Mortgage Lead Quality Metrics That Predict Funding
Track mortgage lead quality metrics that predict funding, from contact rate to cost per funded loan. Call (510)-663-7016 to sharpen your lead audit.
By Tobias Ravencrest
A high contact rate feels like progress. A funded loan pays the bills. Too many mortgage professionals celebrate the first and wonder why the second never arrives. The gap between those two outcomes is where lead quality lives, and it is measurable if you know which numbers to watch. Mortgage lead quality metrics that predict funding are not the vanity figures most dashboards highlight. They are the ratios that trace a straight line from first dial to closed loan, and they expose whether a lead source is feeding your pipeline or merely filling it.
This article breaks down the quality chain that matters, explains why a strong contact rate can mask a weak source, shows how to audit vendors by funded outcomes instead of volume, and explains how return policies act as a quality backstop. It is written for loan officers, brokers, and lending institutions that buy leads and need to defend every dollar of marketing spend with evidence.
The Quality Chain: Contact Rate, Application Rate, Funded Rate
Lead quality is not a single number. It is a sequence of conversion rates, each one narrowing the pool of prospects until only funded loans remain. The first link is contact rate: the percentage of delivered leads you actually reach by phone, text, or email within a defined window. The second is application rate: the percentage of contacted leads who complete a full application. The third is funded rate: the percentage of applications that close. Each link tells a different story, and the ratio between them reveals where a lead source is strong or broken.
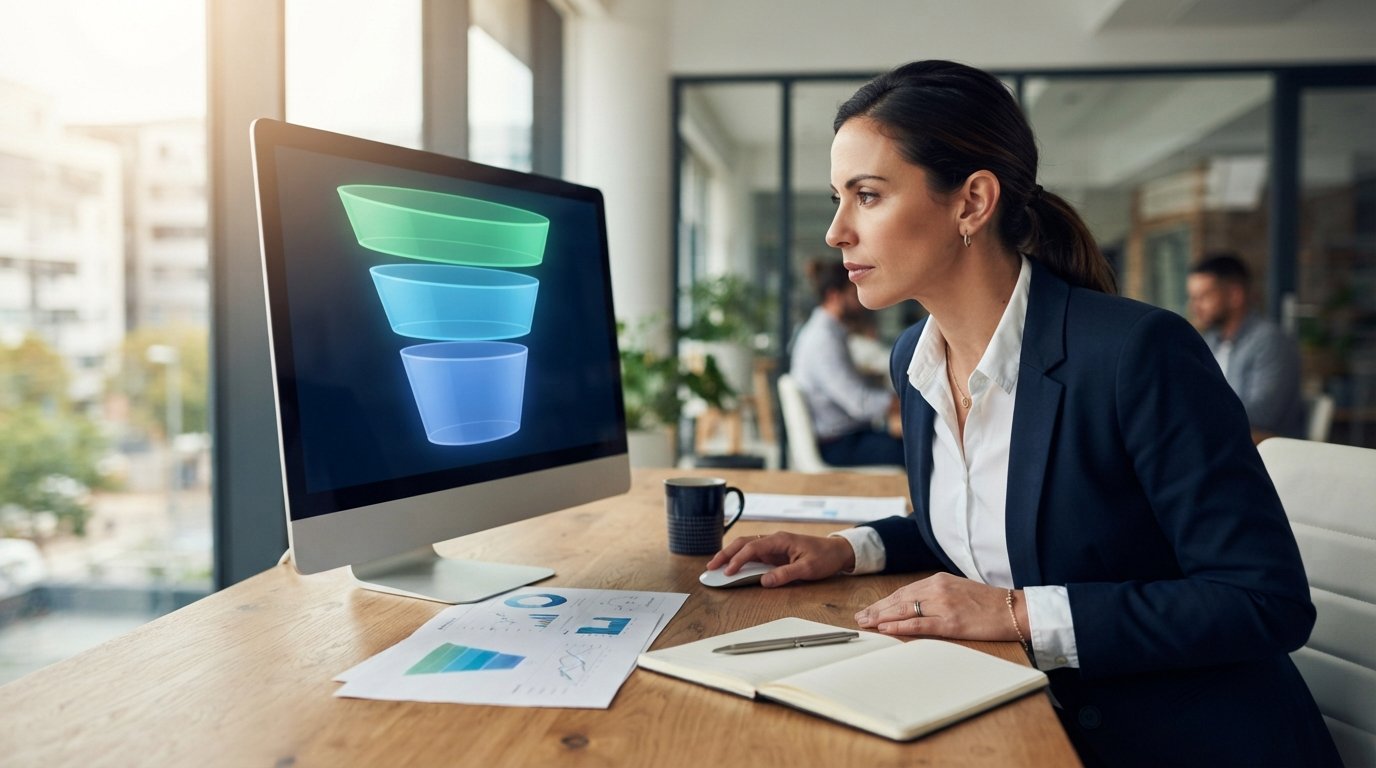
A useful way to think about this is to track the chain as a single funnel for every source you buy from. If a vendor delivers 1,000 leads, a 40 percent contact rate gives you 400 conversations. A 25 percent application rate on those conversations gives you 100 applications. A 20 percent funded rate on those applications gives you 20 loans. Change any one ratio and the funded outcome moves dramatically, which is why volume alone is a misleading buying signal.
Here is how to structure the audit so the chain is visible at a glance:
- Contact rate: leads reached within 24 hours divided by total leads delivered.
- Application rate: completed applications divided by leads contacted.
- Funded rate: funded loans divided by completed applications.
- Cost per funded loan: total lead spend divided by funded loans.
The final metric, cost per funded loan, is the one that belongs in every vendor review. A source with a lower sticker price but a weak funded rate can cost more per closed loan than a premium source with strong intent. Mortgage lead quality metrics that predict funding always resolve to this number eventually, because it is the only figure that connects marketing spend to revenue.
Why a High Contact Rate Does Not Guarantee Conversion
Contact rate is the easiest metric to inflate and the easiest to misread. A lead can be reachable and still be unqualified: wrong loan type, credit profile far outside program guidelines, property that will not appraise, or a consumer who was never serious about borrowing. When a source optimizes for contactability alone, it can deliver leads that answer the phone but never complete an application, and the contact rate looks healthy while the funded rate collapses.
This is the trap that many professionals fall into when they evaluate a new vendor for the first time. They see a 60 percent contact rate in week one and assume the source is strong. Two months later, applications are thin and the cost per funded loan is triple what a more selective source produces. The lesson is that contact rate must always be read alongside application rate. A source with a 35 percent contact rate and a 40 percent application rate is usually far more valuable than a source with a 60 percent contact rate and a 10 percent application rate.
There is a second layer to this problem: speed. Contact rate measured over 72 hours hides the fact that most mortgage intent decays within the first hour. A lead that answers on day three is rarely the same prospect who was shopping on day one. When you audit vendors, measure contact rate in tight windows (first 15 minutes, first hour, first 24 hours) and compare those windows to application rate. If the early-contact leads convert at a much higher rate, the source is delivering real-time intent. If conversion is flat across all windows, the leads may be recycled or aged.
For a deeper look at why some internet lead purchases fail for reasons that have nothing to do with the vendor, the breakdown of why internet mortgage leads did not work covers common operational mistakes that distort every downstream metric.
Auditing Lead Sources by Funded Outcomes, Not Volume
The most common mistake in lead buying is judging a source by how many leads it can deliver. Volume is a capacity metric, not a quality metric. A vendor that can send 500 leads a month is only useful if a predictable percentage of those leads fund. Auditing by funded outcomes flips the conversation from "how many can you send" to "how many close," and that shift changes which vendors survive in your budget.
A practical audit runs on a rolling 90-day window per source. Pull every lead delivered, every contact attempt, every application, and every funded loan, then calculate the chain ratios described earlier. Segment the results by loan type, geography, and lead format, because a source that performs well on refinance leads may underperform on purchase leads, and exclusive leads almost always outperform shared leads on application rate. The goal is not a single grade for the vendor but a map of where that vendor actually produces funded loans.
When you run this audit, keep three rules in mind. First, attribute every funded loan back to the original lead ID, not to the campaign name, or the data will blur. Second, exclude leads that were returned under policy, since those never had a fair chance to convert. Third, compare vendors on cost per funded loan rather than cost per lead, because that is the number your CFO will ask about. A source that charges more per lead but funds at twice the rate is usually the cheaper source in the end.
This is also where a lead exchange platform earns its place in the process. Buying from a marketplace that verifies mortgage-specific intent before distribution, filters by geography and demographics, and supports exclusive, shared, and live transfer formats gives you cleaner inputs for the audit. Live transfers, for example, connect you to a consumer on the phone with a short buffer before the call, which removes the contact-rate variable almost entirely and lets you judge the source on application and funded rates alone. Platforms built for pay-per-call acquisition, such as PayPerCall Marketing, follow a similar logic: you pay for qualified conversations, not raw clicks, which makes the quality chain easier to measure from the first dial.
Using Return Policies as a Quality Backstop
No audit is perfect, and even a well-run lead program will receive some leads that are unreachable, duplicate, or clearly outside the stated criteria. Return policies exist to absorb that noise. A strong return policy credits or replaces leads that meet defined failure conditions within a defined window, which protects the funded-rate math from being polluted by leads that never had a chance. Without a backstop, every bad lead drags down your ratios and makes good sources look mediocre.
Read return policies carefully before you buy, and treat them as a quality signal in their own right. A vendor that offers a clear, agent-friendly return process is usually confident in its verification. A vendor that hides returns behind vague language or short windows is telling you something about its lead hygiene. The policy should specify what counts as a returnable lead (wrong number, disconnected, duplicate, outside geography, wrong loan type), how long you have to submit a return, and how credits are issued.
Operationally, build returns into your workflow instead of treating them as an afterthought. Log every return with a reason code, review return rates weekly, and watch for spikes. A sudden rise in unreachable leads from one source is an early warning that lead quality is slipping before it shows up in your funded rate. When return rates stay low and funded rates stay high, you have a source worth scaling. When returns climb and applications fall, it is time to renegotiate or replace the source.
Building a Scorecard That Predicts Funding
Once you have the chain ratios, the audit process, and the return backstop in place, consolidate everything into a one-page scorecard per source. The scorecard should show contact rate by time window, application rate, funded rate, cost per funded loan, return rate, and average days to fund. Review it monthly and rank sources by cost per funded loan, not by lead volume. This single habit will change how you allocate budget and which vendors you keep.
Mortgage lead quality metrics that predict funding are ultimately about discipline. The numbers are not complicated, but they require consistent attribution, honest segmentation, and a willingness to cut sources that look busy but do not close. Professionals who run this playbook stop asking vendors how many leads they can send and start asking how many loans their leads have funded. That question, backed by a scorecard and a return policy, is the difference between a pipeline that looks full and a pipeline that pays.
Start with one source this month. Pull the last 90 days of data, calculate the chain, and compare cost per funded loan against your next best source. The answer will tell you more about lead quality than any sales pitch ever could.