Winning Mortgage Lead Competition With Online Lenders on Speed
Master mortgage lead competition with online lenders on speed. Call (510)-663-7016 to learn how real-time leads and fast follow-up win borrowers.
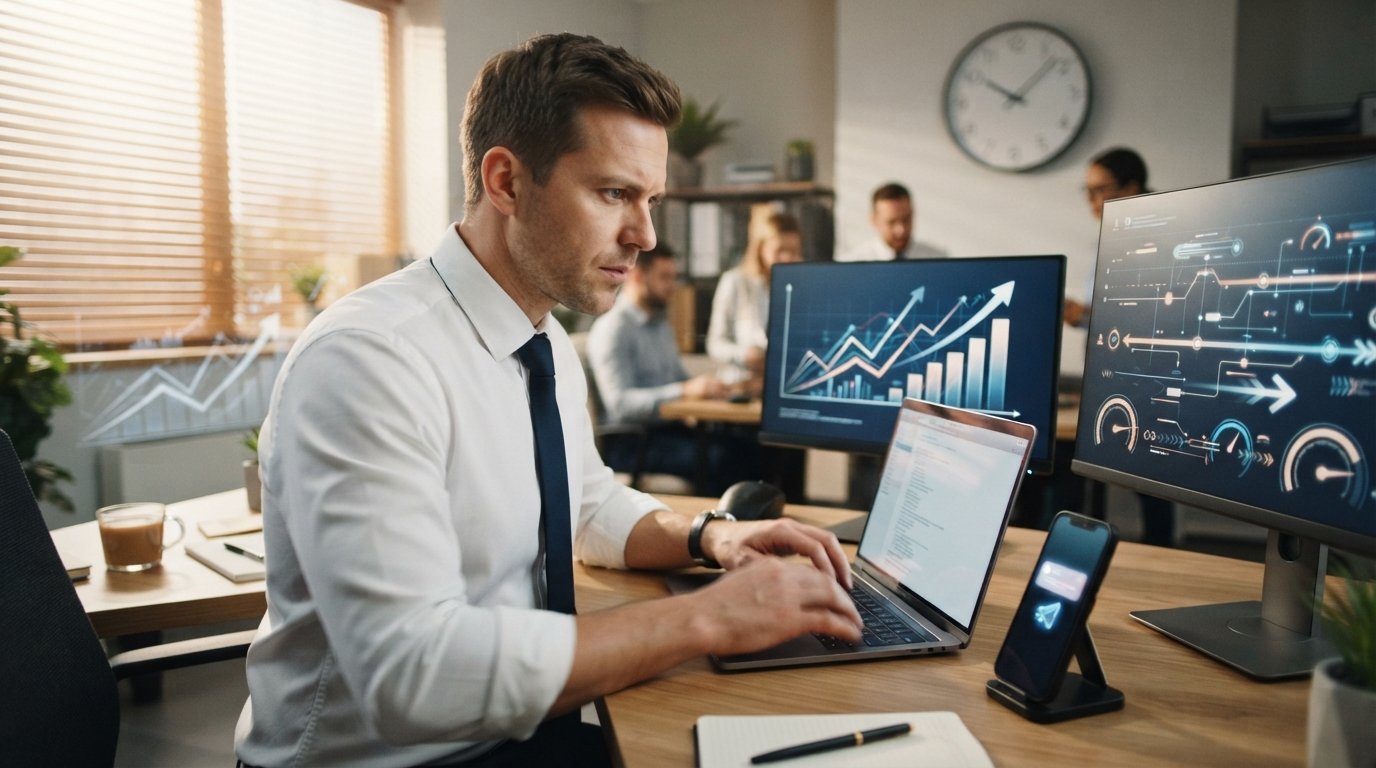
When a borrower submits a mortgage inquiry, the clock starts ticking, and it ticks loudly. Online lenders often respond within seconds, sending automated quotes and preapproval offers before a local loan officer has even opened the lead record. That gap is the heart of mortgage lead competition with online lenders on speed, and it decides who gets the conversation, and ultimately, who gets the loan. The good news is that speed is not a fixed trait; it is an operational choice. With the right data, workflow, and follow-up cadence, local mortgage professionals can compete head-to-head with digital-first lenders and win on the strength of both responsiveness and relationship.
Why Speed-to-Contact Still Decides Many Lead Outcomes
Consumer attention is perishable. When someone requests mortgage information, they are often comparing several lenders at once, and the first credible response shapes their perception of the entire market. Studies across lead-driven industries consistently show that contacting a lead within the first five minutes dramatically increases the chance of a meaningful conversation, while delays of even thirty minutes can cut contact rates in half. In mortgage lending, where the decision involves large sums and long-term commitment, the first responder gains a psychological advantage: they become the baseline against which every other offer is judged.
The reason is simple. Borrowers are not just shopping for a rate; they are shopping for certainty. An instant response signals competence, availability, and technological sophistication. A slow response signals the opposite, even if the loan officer behind it is more experienced and better equipped to solve the borrower's problem. This is why mortgage lead competition with online lenders on speed is not merely a marketing concern; it is a core operational metric that loan officers and branch managers should track as closely as pull-through rate.
However, speed alone is not a strategy. A fast but generic response can be just as off-putting as a slow one. The winning formula combines rapid acknowledgment with a personalized, knowledgeable follow-up. The first touch can be automated, but the second touch must be human, relevant, and grounded in the borrower's stated needs. When you buy mortgage leads from a marketplace like MortgageLeads.com, you gain access to real-time inquiries that can be routed instantly to the right loan officer, which is the first step toward compressing that critical response window.
What Consumers Expect From Digital-First Mortgage Experiences
Borrowers have been trained by the rest of e-commerce to expect immediacy. They can apply for a credit card, open a bank account, or get an insurance quote in minutes, and they carry those expectations into mortgage shopping. A digital-first mortgage experience typically includes instant prequalification, transparent rate ranges, document upload portals, and status tracking. Online lenders have built their entire brands around these features, and they market them aggressively.
But consumers also report frustration with faceless digital processes. They want speed, but they also want answers. They want to know why a rate changed, what documents matter, and how a local market factor might affect their loan. This is the opening for local lenders: match the digital convenience, then exceed it with human guidance. The competition on speed does not mean you must become a fully automated lender; it means you must remove friction from the early stages of the borrower journey.
Consider what borrowers actually experience when they submit a request through a high-intent lead source. They may receive a text message, an email, and a phone call from multiple providers within minutes. Your response must stand out not only by being fast but by being clear and useful. A short message that references the borrower's specific scenario (for example, a cash-out refinance inquiry or a first-time purchase in a particular neighborhood) will outperform a generic rate quote every time. If you are working on the purchase side, our guide on how to generate first-time home buyer mortgage leads covers additional strategies for reaching borrowers early in their journey.
Differentiating on Guidance and Local Expertise
Online lenders compete on convenience and often on headline rates, but they frequently fall short on nuanced guidance. A borrower with self-employment income, a complex property type, or a tight timeline needs more than an algorithm; they need a professional who can interpret guidelines and advocate on their behalf. Local lenders can lean into this advantage by positioning themselves as the expert who answers the phone and explains the trade-offs.
Differentiation starts with the first conversation. Instead of leading with a rate quote, lead with a question: What is the borrower trying to accomplish, and what is their timeline? This approach slows the conversation down just enough to build trust while still respecting the borrower's need for speed. It also creates an opportunity to educate the borrower on factors that online quotes often ignore, such as closing costs, mortgage insurance, and local tax implications.
Another differentiator is responsiveness across channels. Some borrowers prefer text, others prefer email, and some want a phone call immediately. A local lender who offers all three and responds quickly on the borrower's preferred channel will often win against a digital competitor that only offers a web portal. The key is to capture channel preference at the point of lead intake and route the lead accordingly. This is where a lead marketplace with real-time delivery and filtering options becomes valuable: you can specify the types of leads and the geographic areas that fit your team's strengths, then respond through the channel the borrower chose.
Operational Changes That Shorten Time From Lead to Conversation
Closing the speed gap requires changes to workflow, staffing, and technology. The goal is to reduce the time between lead arrival and a meaningful human conversation to minutes, not hours. Here are the operational levers that matter most.
- Instant lead routing. Leads should be delivered to a specific loan officer or team in real time, not to a shared inbox. Routing rules can be based on geography, loan type, or availability, ensuring the right person gets the lead immediately.
- Automated first touch. A text message and email can go out within seconds of lead arrival, acknowledging the inquiry and setting expectations for a call. This buys time for the loan officer to review the details and prepare a personalized response.
- Call cadence and coverage. Set a standard for how quickly calls are attempted and how many attempts are made. Many teams use a two-minute call rule during business hours and a next-morning rule for after-hours leads, with text follow-up in between.
- CRM integration and visibility. The lead source should integrate with your CRM so that every touch is logged and no lead falls through the cracks. API integration with quoting engines and CRMs, such as the options available through MortgageLeads.com, allows lead data to flow directly into your workflow without manual entry.
- After-hours coverage. Online lenders do not sleep, and borrowers often submit inquiries at night. A rotating on-call schedule or a virtual assistant service can ensure that after-hours leads receive a prompt response, even if the full conversation happens the next morning.
These changes are not expensive, but they do require discipline. The most successful teams treat speed-to-contact as a key performance indicator and review it weekly. They also measure contact rate by lead source and time of day, which helps identify where the process breaks down. When you buy mortgage leads, ask about delivery speed and routing options; a provider that delivers leads in real time with flexible filters gives you a stronger starting position in the race against online lenders.
Realistic Expectations: No Guarantees on Conversion
Speed improves the odds of a conversation, but it does not guarantee a loan. Borrowers will still compare offers, change their minds, or discover that they do not qualify for the product they wanted. Responsible lead providers are clear about this: buying leads does not guarantee sales, close rates, or specific volumes. What it does guarantee is access to consumers who have expressed interest, and the rest depends on how well you respond and advise.
It is also important to set realistic internal expectations. A faster response will lift contact rates, but the conversion from conversation to application depends on product fit, pricing, and the borrower's timeline. Teams should track the full funnel, from lead to contact to application to closing, and adjust their strategy based on data rather than anecdote. If a particular lead type or geographic area underperforms, refine the filters rather than abandoning the channel.
Another realistic consideration is compliance. Speed cannot come at the expense of proper consent, disclosure, and documentation. Work with lead providers that verify consumer intent and provide clear compliance documentation. MortgageLeads.com, for example, verifies leads for mortgage-specific intent before distribution, which helps protect your team from wasted effort and regulatory risk. For professionals who also serve senior borrowers, understanding adjacent markets can be useful; the educational resources at MedicareLeads.com explain how Medicare plan inquiries are generated and verified, offering a useful comparison for how intent verification works in another financial lead vertical.
Building a Speed-First Culture Without Sacrificing Advice
The tension between speed and advice is real, but it is not insurmountable. The best loan officers use speed to earn the right to advise. They respond fast, acknowledge the borrower's situation, and then slow down just enough to ask the questions that reveal the right solution. This approach works because it respects the borrower's time while demonstrating expertise.
To build a speed-first culture, start with clear standards and the tools to meet them. Define what "fast" means for your team, whether that is a two-minute call attempt or a five-minute text response, and make those standards visible. Then remove the friction that slows people down: pre-written templates, mobile access to the CRM, and lead routing that does not require manual sorting. Finally, recognize and reward responsiveness, not just closed loans. When loan officers see that speed is valued, they will prioritize it.
It also helps to think about speed as a competitive story you can tell borrowers. When a borrower receives a fast, personalized response from a local lender, that experience becomes part of your brand. They may tell friends, leave a positive review, or return for their next refinance. In a market where online lenders spend heavily on marketing, earned reputation is a powerful counterweight.
Mortgage lead competition with online lenders on speed is not a battle that local professionals are destined to lose. By combining real-time lead delivery, automated first touches, disciplined call cadence, and genuine local expertise, you can meet borrowers where they are and give them a reason to choose you over an algorithm. The race is won in minutes, but the relationship is won in the conversations that follow.