Home Seller Leads for Cash Offer and iBuyer Markets
Reach sellers weighing cash offers and iBuyers with a financed purchase strategy. Call (510)-663-7016 to confirm current home seller lead terms.
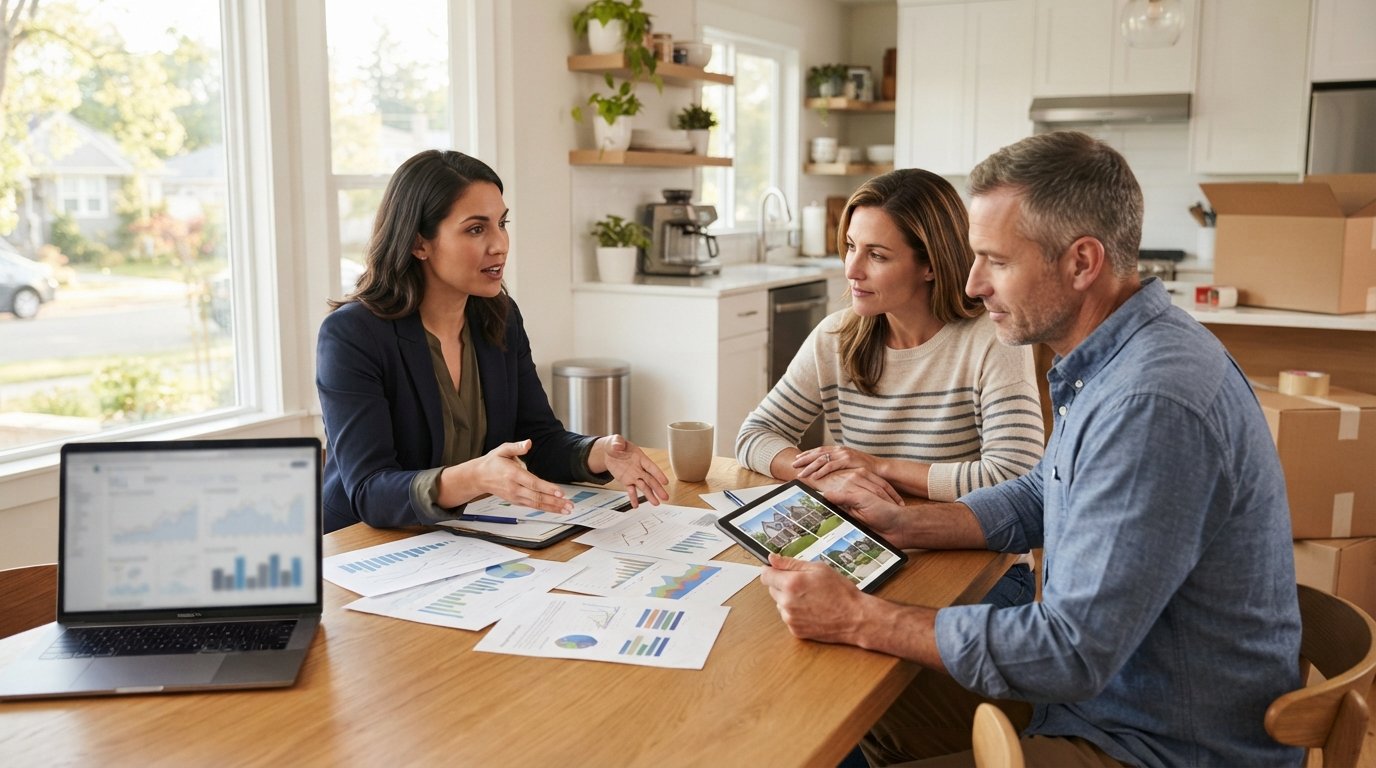
The rise of instant-offer buyers and iBuyer platforms has changed how homeowners think about selling. Sellers now compare a traditional listing against a cash offer before they ever call an agent or a lender. For mortgage professionals, that shift creates both a threat and an opening. The threat is losing purchase pipeline to all-cash buyers. The opening is a new category of high-intent leads: home seller leads for cash offer and iBuyer markets. These are homeowners who have raised their hand about selling, often with a timeline and a motivation already in motion. If you can reach them while they are still comparing options, you can position a financed purchase as the stronger path.
This article breaks down what these leads reveal, how to compete against cash offers, how to build follow-up sequences that keep conversations alive, and how to convert seller conversations into a predictable purchase pipeline. It also covers the practical step of confirming current lead terms with your provider before you scale spend. The goal is not to fight the iBuyer model. The goal is to win the seller who has not yet decided which path to take.
What Home Seller Leads Reveal About Timeline and Motivation
A home seller lead is not a generic mortgage inquiry. It usually starts with a consumer who has expressed interest in selling, requesting a cash offer, or exploring an instant sale. That expression of interest carries two valuable data points: timeline and motivation. A seller who requests a cash offer in the next 30 days is in a different situation than one who is curious about home values six months out. Treating both the same wastes time and budget.
Timeline is the strongest signal. Instant-offer shoppers often fall into three rough buckets. The first is urgency: job relocation, divorce, inherited property, or financial pressure. The second is convenience: they want to skip repairs, showings, and contingencies. The third is curiosity: they are testing the market and have no firm plan. Urgency and convenience sellers are your best prospects because a financed offer can still solve their problem, often at a higher net price. Curiosity sellers need education and longer nurture.
Motivation tells you which argument to lead with. A seller facing a tight deadline cares about certainty and speed. A seller who wants to avoid repairs cares about as-is options and net proceeds. A seller who is downsizing cares about buying their next home without a gap. When you review home seller leads, look for the fields that indicate reason for selling, desired timeline, property condition, and whether they have already requested an offer. These details let you segment before the first call.
Lead quality also depends on how the inquiry was captured. A form fill on a cash-offer landing page is intent-rich but may be early. A live transfer or inbound call is usually further along. Shared leads may be sold to multiple buyers, so speed matters. The practical takeaway is simple: sort by timeline first, then by motivation, then by lead type. A seller with a 30-day deadline and a live transfer is worth a call within minutes, not hours.
Positioning a Traditional Sale Plus Purchase Mortgage Against Cash Offers
Cash offers win on certainty and speed. That is their entire pitch. A financed offer can compete, but only if you translate its advantages into the seller's language. Most sellers do not care about loan products. They care about net proceeds, closing dates, repair requests, and the risk of a deal falling through. Your job is to show how a financed buyer, especially one who is pre-approved, can match the certainty of cash while delivering a higher price.
The strongest positioning starts with net proceeds. Cash buyers and iBuyers typically discount for speed and risk. A traditional sale often nets more even after commissions and concessions. Run the comparison for the seller in plain numbers: estimated cash offer, estimated listing price, likely repair credits, and closing timeline. Do not promise a specific price, but do show the range and the trade-offs. When the gap is meaningful, the seller will listen.
Certainty is the second argument. A pre-approved buyer with a verified income and asset file is not the same as a speculative buyer. You can strengthen the offer by educating the seller on appraisal contingencies, financing timelines, and what a clean pre-approval actually means. If your borrower can be flexible on the closing date, say so. Flexibility reduces the seller's risk of a double move or a gap between transactions.
Convenience is the third argument. Many sellers assume a cash offer is the only way to avoid repairs and showings. In reality, a financed buyer can accept a home as-is, and some renovation loan products let the buyer finance repairs after closing. Showings can be minimized with strong marketing and a clear timeline. When you frame the traditional sale as flexible rather than rigid, the cash-offer advantage shrinks.
There is also a practical conversation to have about the next purchase. Many sellers are also buyers. A cash offer solves the sale but does nothing for the purchase unless the seller has another financing plan. A mortgage professional who can coordinate both sides offers something an iBuyer cannot: a single point of contact for the sale and the next loan. That is a genuine differentiator, and it belongs in your first conversation.
Follow-Up Sequences for Sellers Still Comparing Options
Most home seller leads are not ready on day one. They are comparing. That means your follow-up sequence matters more than your first call. The goal is to stay present, add value, and be the person they call when they decide. A good sequence mixes speed, education, and check-ins without becoming noise.
The first touch should happen fast. If the lead arrives as a live transfer, you are already in conversation. If it arrives as a form fill, call within five minutes during business hours and within the first hour after hours. Speed is a competitive advantage, especially with shared leads. If you cannot reach them, send a short text or email that references their inquiry and offers a specific next step, such as a quick net proceeds comparison.
After the first touch, build a sequence that respects the seller's timeline. A seller with a 30-day deadline needs daily or every-other-day contact. A seller six months out needs a monthly value touch. Here is a simple framework that works for most teams:
- Day 0: Call and text within minutes. Leave a short voicemail that names the cash-offer comparison and offers a no-pressure review.
- Day 1 to 3: Send an email with a one-page comparison of cash offer versus traditional sale, including net proceeds and timeline.
- Day 4 to 7: Call again with a specific question, such as whether they have received a cash offer yet and what number they were quoted.
- Week 2 to 4: Switch to value touches. Share a local market update, a short video on as-is sales, or a checklist for preparing a home for a financed buyer.
- Month 2 and beyond: Monthly check-ins with a clear offer to rerun the numbers when they are ready.
The content of the follow-up should always tie back to the seller's stated motivation. If they want to avoid repairs, send information on as-is financing and renovation loans. If they are relocating, send a timeline that shows how a financed sale can align with their move date. If they are comparing cash offers, ask what number they were quoted and offer to review it. Specificity beats generic check-ins.
Track responses and adjust. A seller who opens every email but never calls may prefer written communication. A seller who answers texts but not calls may be busy during the day. Small signals tell you how to stay in touch without burning the relationship. The sequence is not a script. It is a system for staying useful until the seller is ready.
Turning Seller Conversations Into Purchase Pipeline
A seller conversation is only valuable if it turns into a purchase pipeline. That means moving from the sale to the next loan. Many sellers are also buyers, and even those who are not yet looking will need financing eventually. Your job is to make that transition natural rather than pushy.
Start by asking about the next move. Where are they going, when, and how do they plan to pay for it? If they are buying, you can pre-approve them before the sale closes, which strengthens their position on both sides. If they are renting for a while, you can set a follow-up for when they are ready. The key is to capture the next transaction while the seller conversation is still warm.
Use a simple handoff framework. First, confirm the sale timeline and the cash-offer comparison. Second, ask about the next home and whether they have spoken to a lender. Third, offer a pre-approval review that accounts for the sale proceeds. Fourth, set a specific follow-up date. This turns a single conversation into a relationship with a defined next step. For teams that buy leads at volume, the same framework can be applied across the pipeline with clear stages and reminders.
There is also a data angle. Seller leads often include property details and motivation fields that can inform your purchase pipeline. A seller downsizing in a specific ZIP code is a future buyer in a nearby market. A seller relocating for work is a future buyer in another state. If your lead provider supports filtering by geography and demographics, use those filters to align seller leads with the markets where you can actually lend. For a deeper look at how product-specific lead buying works, including compliance and availability questions, see this guide on buying FHA leads in California. The same discipline applies to seller leads: know the rules, verify the terms, and match the lead to your capacity.
Finally, measure what matters. Track contact rate, conversation rate, cash-offer comparison rate, and purchase conversion rate. A seller lead that never converts to a purchase conversation is a cost. A seller lead that becomes a pre-approval is an asset. Review these numbers monthly and adjust your sequence, your filters, and your budget accordingly.
Confirming Current Home Seller Lead Terms With Your Provider
Lead terms change. Pricing, filters, exclusivity, return policies, and delivery methods can shift with market conditions and provider updates. Before you scale spend on home seller leads for cash offer and iBuyer markets, confirm the current terms in writing. This is not a one-time step. It should be part of your quarterly review.
Ask specific questions. Are the leads exclusive or shared? How many buyers receive the same lead? What is the return policy, and what qualifies as a return? Are live transfers available, and what is the contact rate? Can you filter by timeline, motivation, or property condition? What is the pricing structure, and does it vary by geography or lead type? Get answers in writing and keep them with your campaign notes.
Also confirm how the provider sources and verifies seller leads. A lead that starts with a cash-offer request is different from a generic home value inquiry. Ask how intent is verified and whether the consumer has consented to be contacted. Compliance matters, especially when you are calling consumers who may be on do-not-call lists. A reputable provider will have clear answers and a process you can document.
If you also work with legal or professional service clients, the same discipline applies to other lead categories. Platforms such as AttorneyLeads provide pre-screened legal leads with real-time delivery, and the verification standards are similar: confirm consent, confirm exclusivity, and confirm return terms before you buy. The principle is universal. Know what you are buying before you scale.
Once terms are confirmed, set a test budget. Run a small batch, measure contact and conversion rates, and compare against your existing purchase pipeline. If the numbers work, scale gradually. If they do not, adjust the filters or the sequence before increasing spend. The goal is a repeatable system, not a one-time campaign.
Building a Repeatable Seller Lead Strategy
The cash-offer and iBuyer market is not going away. Sellers will continue to compare instant offers against traditional sales, and mortgage professionals who can speak to that comparison will win more purchase pipeline. The strategy is straightforward: segment by timeline and motivation, position financed offers on net proceeds and certainty, follow up with a sequence that respects the seller's timeline, and convert seller conversations into purchase pre-approvals. Confirm your lead terms, test small, and scale what works.
MortgageLeads.com supports this strategy with home seller leads and a broader exchange for refinance, new purchase, home equity, and reverse mortgage leads. Leads can be filtered by geography and demographics, delivered as exclusive or shared, and integrated with your CRM through API. Pricing and terms can change, so confirm current packages on the product pages before you buy. With the right filters and a disciplined follow-up system, seller leads become more than a hedge against cash offers. They become a predictable source of purchase pipeline.