Mortgage Lead Management Workflow: Intake to Closing
A step-by-step mortgage lead management workflow from intake to closing, covering validation, routing, nurture, and returns. Call (510)-663-7016.
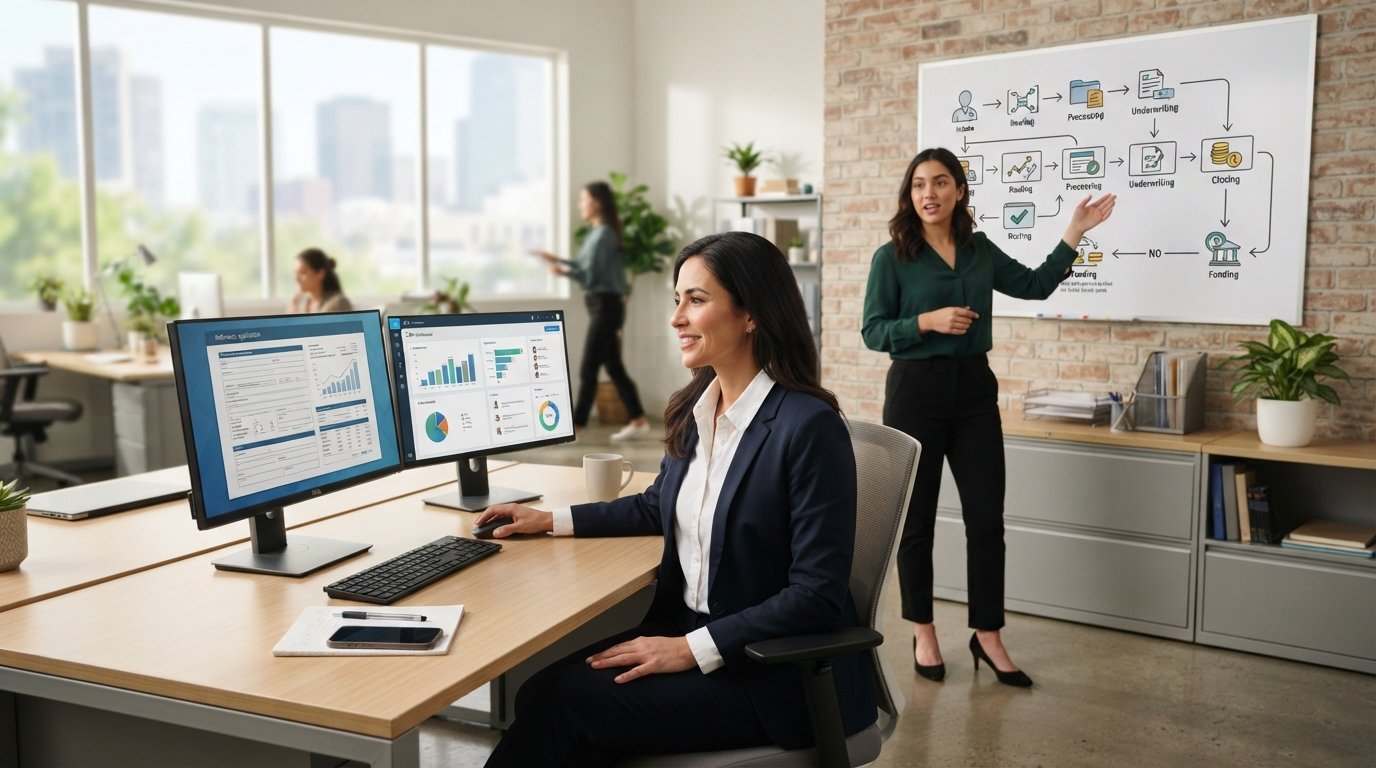
A lead arrives at 9:47 a.m. on a Tuesday. It is a refinance inquiry from a homeowner in the Pacific Northwest who has been with the same lender for eleven years. If that lead sits untouched for two hours, the odds of a meaningful conversation drop sharply. If it is routed to the wrong loan officer, the borrower feels the friction immediately. And if the source and consent details are never documented, the file becomes a compliance liability long before it ever reaches the closing table. The difference between a funded loan and a wasted opportunity almost never comes down to lead volume. It comes down to the workflow that sits between the moment of intake and the moment of closing. That is the mortgage lead management workflow from intake to closing, and it is the operational backbone of every high-performing lending team.
This guide walks through that workflow step by step, from the validation checks that happen before a lead ever touches your CRM, through assignment and routing, nurture and re-engagement, and finally the handoff to processing where source attribution and return window rules protect both your investment and your compliance posture. Along the way, it shows where a platform like MortgageLeads.com fits into the picture, because the quality of the intake source shapes everything that follows.
Why the Intake-to-Closing Workflow Determines Lead ROI
Most mortgage professionals think about lead generation and lead conversion as two separate activities. In practice, they are one continuous process, and the handoffs between them are where money leaks out. A lead that is purchased, delivered, and then left to sit in a shared inbox is not really a lead at all. It is an unworked asset. The same inquiry, routed within minutes to a loan officer with the right product expertise and followed through a defined sequence, becomes a pipeline entry with a realistic path to funding.
The workflow matters even more when you are buying leads rather than generating them organically. Purchased leads carry a cost per unit, a return window, and often a set of status rules that determine whether you can get credit for a bad contact, a duplicate, or a borrower who was never genuinely interested. If your team does not have a documented process for intake validation, assignment, nurture, and documentation, you will lose money on returns you never claimed and conversions you never gave yourself a chance to earn. The workflow is not administrative overhead. It is the mechanism that turns a lead cost into a loan.
There is also a compliance dimension that many teams underestimate. Mortgage leads arrive with consent records, TCPA considerations, and source attribution that need to be preserved. When a regulator or an auditor asks where a borrower came from and how consent was obtained, the answer needs to live in the file, not in someone's memory. A well-designed workflow captures that information at intake and carries it through to closing.
Stage One: Intake Validation Before the CRM
The first stage of the workflow happens before the lead enters your CRM, and it is the stage most teams skip. Intake validation is the set of checks that confirm a lead is real, reachable, and appropriate for your lending operation. It is not about second-guessing the source. It is about protecting your loan officers' time and preserving your return eligibility. A lead that fails validation should be flagged and returned within the window, not assigned to an officer who will spend twenty minutes dialing a disconnected number.
Validation should cover several dimensions. Contact data needs to be checked for formatting and plausibility, including phone number structure and email syntax. Duplicate detection should run against your existing CRM records so the same borrower is not worked by two officers or purchased twice. Consent and source fields should be present and legible, because those fields feed both compliance and return claims. And the lead should be checked against your product and geographic filters, since a reverse mortgage inquiry routed to a purchase-focused officer is a wasted assignment regardless of how good the lead is.
A practical validation checklist looks like this:
- Confirm phone and email data are complete and correctly formatted, with no placeholder or obviously invalid entries.
- Run duplicate detection against active CRM records and recent lead purchases to prevent double-work.
- Verify that consent language, source identifier, and timestamp are present and stored with the lead record.
- Check that the lead matches your product focus, geography, and licensing coverage before assignment.
- Flag any lead that fails a check and route it to a return queue rather than to a loan officer.
This is also where your lead source matters. A platform that verifies mortgage-specific intent before distribution reduces the volume of junk that reaches your validation step, which means your team spends less time disqualifying leads and more time working real ones. MortgageLeads.com, for example, sources consumer inquiries through digital channels and verifies them for mortgage intent before distributing them to subscribers, which gives your intake validation a cleaner starting point. The platform also supports filtering by geographic and demographic criteria, so the leads you receive are already closer to your target profile. You can see how this plays out in specific markets in resources like the guide on generating quality Los Angeles mortgage leads, where local targeting and intake discipline reinforce each other.
Stage Two: Assignment and Routing to the Right Loan Officer
Once a lead clears validation, the clock starts. Speed to contact is one of the strongest predictors of conversion in mortgage lead management, and routing decisions determine whether that speed is used well. Assignment is not simply a round-robin distribution. It is a matching problem: the right lead to the right officer, with the right product knowledge, in the right geography, at the right time.
Effective routing rules usually combine several factors. Product expertise comes first, since a refinance lead and a reverse mortgage lead require different conversations and different licensing in some cases. Geography and licensing coverage come next, because an officer who cannot lend in the borrower's state should never receive the lead. Language preference matters in many markets. And capacity matters too: routing to an officer who is already buried in active files creates delay, not speed. Some teams add performance-based routing, sending higher-value leads to officers with stronger conversion histories, though this needs to be balanced against fairness and development goals.
Speed is the non-negotiable element. Best practice is to route leads within minutes of intake, with automated notifications to the assigned officer and an escalation path if the lead is not contacted within a defined window. A simple structure works well:
- Route by product and geography first, so the lead lands with an officer who can actually work it.
- Apply capacity and performance rules second, so high-value leads reach officers with availability and track record.
- Notify the assigned officer immediately through CRM alert, email, and SMS, with the lead details and a suggested call script or product summary.
- Escalate to a backup officer or team lead if no contact attempt is logged within the defined window, typically fifteen to thirty minutes for live transfers and a few hours for form leads.
The escalation step is where many workflows quietly fail. Without it, assignment is a suggestion rather than a commitment. With it, every lead has an owner and a deadline, and the team can measure contact rates by officer, by lead type, and by time of day. That measurement is what allows you to refine routing rules over time rather than guessing.
Stage Three: Nurture and Re-Engagement for Slow-Moving Borrowers
Not every lead is ready to apply today. In fact, a large share of mortgage inquiries are exploratory: a homeowner curious about refinancing, a buyer early in the search process, or a borrower who needs to improve credit before qualifying. The workflow has to account for these borrowers rather than discarding them. Nurture and re-engagement are where long-term pipeline value is created.
The first step is segmentation. After the initial contact attempt, leads should be categorized by readiness: ready to apply, actively shopping, early stage, and not a fit. Each category deserves a different cadence. Ready-to-apply leads move directly to application. Actively shopping leads get a structured follow-up sequence over days and weeks. Early-stage leads enter a longer nurture track with educational content, rate updates, and periodic check-ins. Not-a-fit leads are documented and either returned if eligible or archived with a reason code.
Re-engagement is the discipline of returning to leads that went quiet. A borrower who stopped responding in March may be ready in June, especially if rates moved or their home equity changed. Automated drip campaigns, periodic personal outreach, and trigger-based re-engagement (such as a rate drop alert or a home anniversary message) keep those relationships warm. The key is to preserve the context: the original inquiry details, the prior conversation notes, and the source attribution all need to stay with the record so that re-engagement feels continuous rather than cold.
This stage is also where the economics of lead buying become clear. A lead that converts on the first call is valuable. A lead that converts after ninety days of nurture is equally valuable and often cheaper, because the acquisition cost was already spent. Teams that treat nurture as a core workflow rather than an afterthought consistently get more funded loans from the same lead spend.
Stage Four: Handoff to Processing and Source Attribution
The handoff from loan officer to processor is a workflow moment that deserves more attention than it usually gets. When a lead becomes an application, the file needs to carry forward everything the intake and assignment stages captured: the lead source, the consent record, the original inquiry details, the contact history, and the officer's notes. If those elements are lost in the handoff, the file loses its provenance, and provenance matters for both compliance and reporting.
Source attribution is the practice of tagging every file with where the borrower came from, which campaign or platform delivered the lead, and which officer worked it. This tagging should happen at intake and persist through closing. It allows the team to measure return on lead spend by source, by product, and by geography. It also supports return window claims, because a file that documents a bad contact or a duplicate is a file that can be credited. Without attribution, those claims become guesswork.
A clean handoff includes a documented application summary, the consent and source fields, the full contact log, and a clear note on the borrower's goals and timeline. Processors should be able to open the file and understand the borrower's story without calling the loan officer. That standard reduces delays, prevents re-work, and keeps the borrower experience consistent from first call to closing.
Where Return Windows and Status Rules Fit
Return windows and status rules are not an administrative detail bolted onto the end of the workflow. They are a stage that runs in parallel with intake and early contact, and they need to be built into the process from day one. Most lead providers, including MortgageLeads.com, offer return policies for leads that are unreachable, disconnected, duplicate, or otherwise invalid, but those policies come with time limits and documentation requirements. A lead that is discovered to be bad on day ten may no longer be eligible for credit if the return window closed on day seven.
The workflow should therefore include a defined return review step, typically within the first forty-eight to seventy-two hours after intake. During that window, officers log contact attempts and outcomes, and the operations team reviews flagged leads against the provider's status rules. Common status categories include bad contact, duplicate, not interested, and invalid data, each with its own documentation standard. The review should be fast, consistent, and recorded in the CRM so that patterns can be analyzed over time.
It also helps to understand the lead formats you are working with, because return rules differ by type. Exclusive leads, shared leads, and live transfers each carry different expectations and different credit policies. Live transfers, for instance, connect your officer directly with a consumer and often come with a contact buffer, so the return logic is different from a form lead that may never answer. Building those distinctions into your return review prevents both over-claiming and under-claiming, and it keeps your relationship with the lead provider productive.
Finally, the workflow should connect lead management to the broader home ecosystem your borrowers inhabit. Many mortgage leads are also homeowners planning renovations, and the same borrower who needs a refinance may also be shopping for a contractor. Platforms that connect home improvement professionals with high-intent customers, such as HomeRemodelingLeads, illustrate how adjacent lead categories can inform your understanding of borrower intent and timing. A homeowner inquiring about a kitchen remodel is often a homeowner thinking about home equity, and recognizing those signals can improve how your team prioritizes and nurtures leads.
Building the Workflow Into Your Team's Operating Rhythm
A workflow only works if it is lived daily. That means assigning clear ownership at each stage, defining response-time standards, and reviewing performance on a regular cadence. The intake validation step belongs to operations or a lead desk. Assignment and routing belong to a sales manager or team lead. Nurture belongs to the loan officer with support from marketing automation. The handoff and attribution belong to processing and compliance working together. Return review belongs to operations with input from the sales team.
Weekly reviews should look at contact rates by lead source, conversion rates by officer, return rates by lead type, and time-to-contact metrics. Monthly reviews should examine source-level ROI and refine routing rules. Quarterly reviews should revisit the entire workflow, because lead sources, return policies, and market conditions change. A workflow that was optimized for a purchase-heavy market may need adjustment when refinance volume rises, and the teams that adapt fastest are the ones that treat the workflow as a living system rather than a fixed procedure.
The mortgage lead management workflow from intake to closing is ultimately a discipline of consistency. Validate before you assign. Assign with speed and precision. Nurture without dropping context. Hand off with full documentation. Review returns within the window. Do those things repeatedly, and the same lead volume produces measurably more funded loans. Skip them, and even good leads become expensive noise. The teams that win are not the ones with the most leads. They are the ones with the tightest process between the first inquiry and the closing table.