Mortgage Sales Funnel Stages for Purchased Leads
Map every mortgage sales funnel stage for purchased leads and fix the leaks that cost you funded loans. Call (510)-663-7016 for expert help.
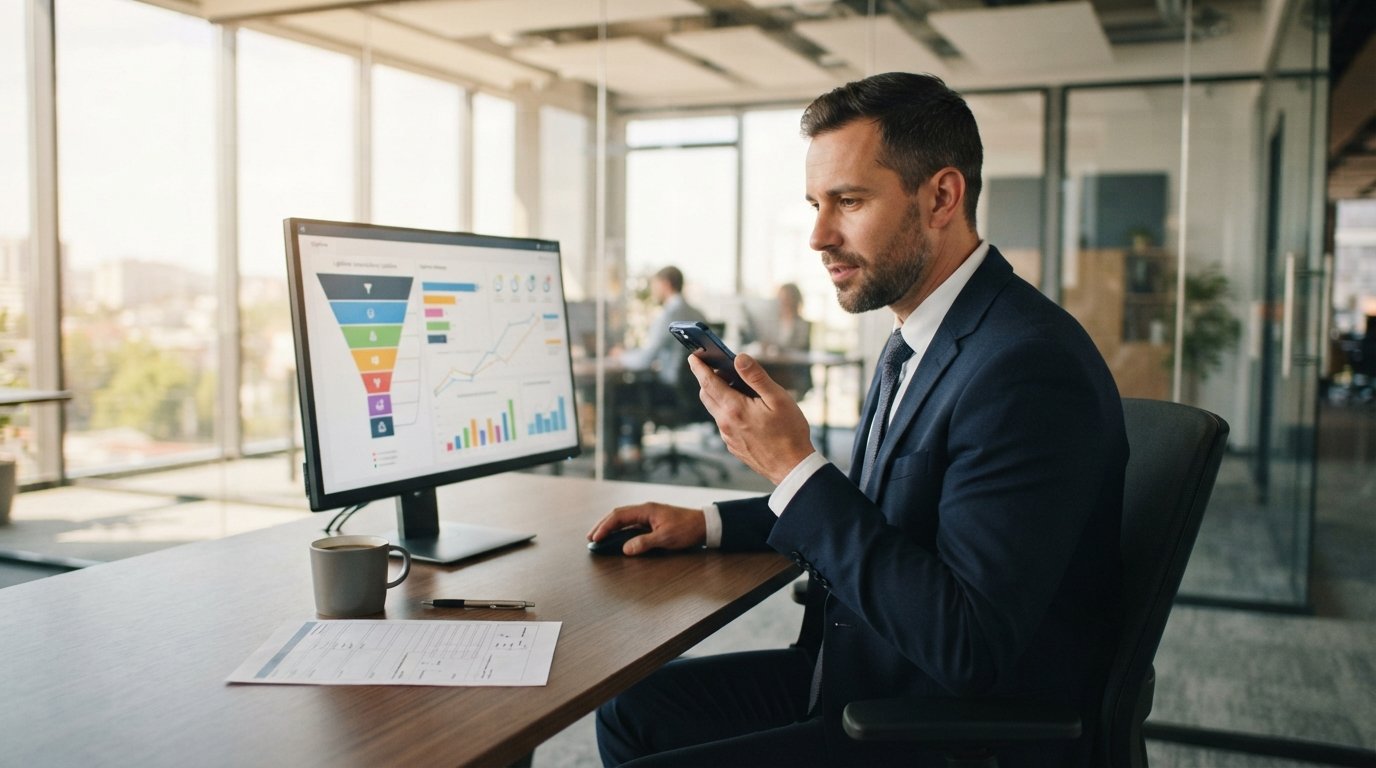
Purchased mortgage leads are not a shortcut to funded loans. They are raw material that must pass through a structured sales funnel before they become revenue. According to industry benchmarks, conversion rates from purchased leads hover between 5 and 15 percent when the funnel is managed correctly, and they fall below 2 percent when it is not. The difference is rarely the lead source itself. It is how the funnel is built, measured, and repaired. This article maps the mortgage sales funnel stages for purchased leads, identifies where deals leak out, and shows you how to fix the weakest links so your cost per funded loan drops and your pipeline stabilizes.
Stage 1: Lead Intake and Qualification
The funnel begins the moment a purchased lead lands in your system. This stage is about speed, accuracy, and fit. A lead that sits untouched for an hour is worth far less than one contacted within five minutes. Research consistently shows that contacting a lead within five minutes makes you nine times more likely to convert that lead compared to waiting even ten minutes. The intake stage is also where you separate leads that match your lending criteria from those that do not. Purchased leads arrive with varying levels of detail. Some include credit score ranges, loan purpose, property state, and contact preferences. Others are thinner. Your intake process should automatically enrich missing data, flag duplicates, and route leads to the right loan officer or team based on geography, loan type, and capacity.
Qualification at intake does not mean a full pre approval conversation. It means confirming three things: the lead is reachable, the lead has a genuine mortgage need, and the lead falls within your product and geographic scope. Skipping this step creates two problems. First, your team wastes time on leads that were never a fit. Second, your CRM fills with noise that makes it impossible to measure true stage conversion rates. A simple intake scorecard can help. Assign points for phone validity, stated intent, timeline, and loan amount range. Leads above a threshold go to immediate outbound calling. Leads below it enter a nurture sequence. This keeps your best resources focused on the highest probability opportunities.
Lead type and exclusivity change the intake stage significantly. Exclusive leads, sold once to you, arrive with no competing calls from other lenders. Shared leads may have been sold to three or four buyers, which means your speed to contact becomes the single biggest variable. Live transfers are different again: the consumer is already on the phone, so intake collapses into a real time qualification conversation. If you are buying live transfers, your intake stage is essentially a warm handoff checklist rather than a callback queue. Understanding which lead format you are working with at intake prevents mismatched expectations and wasted effort.
Stage 2: First Contact and Engagement
First contact is where most purchased lead funnels spring their first major leak. The causes are predictable: slow response, weak opening scripts, poor voicemail strategy, and insufficient contact attempts. A lead that is not reached within the first 24 hours has a dramatically lower chance of ever converting. Yet many loan officers make only one or two call attempts before moving on. High performing teams make five to eight attempts across multiple channels (phone, text, email) over the first week. They also vary the time of day, because a lead who is unavailable at 10 a.m. on a Tuesday may answer at 6 p.m. on a Thursday.
The quality of the first conversation matters as much as the speed. A generic script that launches into rate quotes before establishing rapport will lose the lead's attention. The best first contacts ask two or three targeted questions, confirm the lead's stated need, and set a clear next step. For example: "I see you were exploring a refinance on your home in Denver. Is the goal to lower your payment, shorten your term, or access equity?" That single question does more than a paragraph of product features. It signals that you have read the lead's information and that you are there to solve a specific problem. For more ways to sharpen your opening lines, see our guide on top one liners to upgrade your mortgage sales script.
Drop off at this stage is usually caused by one of four things: the lead was never genuinely interested, the lead was contacted too late, the lead was contacted poorly, or the lead was contacted too many times by competing lenders. You can diagnose which cause is dominant by tracking contact rate (percentage of leads reached) and conversation rate (percentage of reached leads who engage for more than two minutes). If contact rate is low, your problem is speed and persistence. If conversation rate is low, your problem is scripting and relevance. If both are low on shared leads but healthy on exclusive leads, your problem is competition and you should reconsider your lead mix.
Stage 3: Needs Analysis and Pre Qualification
Once a lead engages, the funnel moves into needs analysis. This is where you gather the information required to match the lead with the right loan product and to set realistic expectations. For a purchase lead, that means understanding timeline, down payment resources, credit profile, income documentation, and property type. For a refinance lead, it means understanding current rate, loan balance, equity position, and the borrower's primary goal. For a home equity or HELOC lead, it means understanding available equity, current mortgage terms, and how the funds will be used. This stage is not a full application. It is a structured conversation that produces a loan recommendation and a clear path forward.
Many purchased lead funnels leak here because loan officers rush. They hear a stated goal and immediately jump to a product pitch without confirming eligibility. That creates two problems. First, they may recommend a product the lead cannot qualify for, which damages trust. Second, they miss cross sell opportunities, such as a purchase lead who also needs a HELOC for renovations or a refinance lead who could benefit from a cash out to consolidate debt. A disciplined needs analysis framework prevents both. Use a consistent set of questions, record the answers in your CRM, and score the lead's readiness. Leads that score high move to application. Leads that score low go into a nurture track with specific follow up triggers, such as a rate drop alert or a credit improvement milestone.
Drop off at this stage is often caused by misaligned expectations. A lead who expected a no documentation loan may disengage when asked for pay stubs. A lead who expected a same day approval may lose interest when told the process takes three weeks. Setting expectations early and honestly is not a conversion killer; it is a trust builder. Leads who understand the process are far more likely to complete it. This is also the stage where lead quality differences become obvious. A well sourced lead with verified intent will engage in a substantive needs conversation. A low quality lead will give vague answers or go silent. Tracking the percentage of engaged leads who complete needs analysis gives you a clear read on whether your purchased leads are delivering the quality you paid for.
Stage 4: Application and Documentation
The application stage is where intent becomes commitment. The lead agrees to provide personal and financial information, and the loan officer begins the formal pre approval or application process. This is the stage where purchased lead funnels often experience their steepest drop off. The reasons are well documented: application friction, documentation fatigue, competing offers, and cold feet. A lead who was enthusiastic on the phone may balk when asked to upload bank statements or grant a credit pull. Reducing friction at this stage is one of the highest leverage improvements you can make. Online application links, secure document upload portals, and mobile friendly forms all increase completion rates. So does setting a clear expectation at the end of the needs analysis call: "The next step is a short application that takes about ten minutes. I will send you a secure link right now while we are on the phone."
Documentation collection is the silent killer of purchased lead conversions. Borrowers who are asked for documents in a disorganized way, or who are asked repeatedly for the same items, lose confidence and disengage. A structured document checklist sent immediately after application, combined with automated reminders and a single point of contact, keeps the process moving. Loan officers who use a document tracking system see significantly higher application to approval conversion rates than those who rely on email threads and manual follow up. If your CRM supports it, integrate document requests directly into the application workflow so the borrower sees exactly what is needed and why.
Competition is another major factor at this stage, especially for shared leads. A lead who applied with you may also be applying with two other lenders. Speed and communication become your differentiators. The lender who calls first, explains clearly, and follows up consistently usually wins. This is also where exclusivity pays off. Exclusive leads have no competing lender calling the same consumer, so the application stage is less of a race and more of a relationship. If you are buying shared leads, build in a same day application push and a next day follow up call to keep your file top of mind.
Stage 5: Processing, Underwriting, and Funding
The final stage of the purchased lead funnel runs from application through processing, underwriting, and closing. This is where operational efficiency determines profitability. A lead that reaches application but stalls in processing is still a loss. Common causes of stall include missing documents, appraisal delays, title issues, and underwriting conditions that are not addressed promptly. Each of these is manageable with the right process. A processing checklist that mirrors underwriting requirements, combined with proactive borrower communication at every milestone, keeps files moving. Borrowers who feel informed are less likely to abandon the process or switch lenders mid stream.
Metrics at this stage should go beyond raw volume. Track application to approval rate, approval to closing rate, average days from application to closing, and fall through rate. A fall through rate above 15 percent is a red flag. It usually points to weak pre qualification, incomplete documentation early in the process, or borrowers who were never fully committed. Reviewing fall through reasons monthly and adjusting your intake and needs analysis questions accordingly creates a feedback loop that steadily improves conversion. This is also the stage where lead source quality shows up in the numbers. If leads from a particular source consistently reach application but fail to close, the problem may be lead quality or expectation setting, not your processing team.
For lenders buying leads at scale, the funding stage is also where cost per acquisition becomes clear. Divide total lead spend by funded loans to get your true cost per funded loan. Then compare that to your revenue per loan. If the ratio is healthy, scale the lead source. If it is not, diagnose whether the leak is at intake, contact, needs analysis, application, or processing. Most lenders find that one or two stages account for the majority of lost opportunities. Fixing those stages is far more effective than simply buying more leads. Platforms like PingPost.Exchange offer real time lead distribution and auction models that can help you test different lead sources and formats quickly, which is useful when you are trying to isolate whether a conversion problem is source related or process related.
How Lead Type and Exclusivity Reshape the Funnel
Not all purchased leads behave the same way through the funnel. Exclusive leads, sold to a single buyer, typically show higher contact rates, longer conversations, and better application completion. The trade off is cost. Shared leads are cheaper per lead but require faster response and more aggressive follow up to win the conversion. Live transfers, where the consumer is connected to a loan officer in real time, collapse the first two stages into a single interaction and often produce the highest contact rates, but they demand immediate availability and strong phone skills. Pay per call leads sit somewhere in between, offering a live conversation but often with less pre qualification than a full transfer.
The shape of your funnel should match your lead mix. If you buy primarily exclusive leads, invest in needs analysis and application completion, because your biggest leaks will be there. If you buy shared leads, invest in speed to contact and multi channel follow up, because your biggest leak is competition. If you buy live transfers, invest in transfer acceptance rates and real time qualification scripts. Many lenders run a blended mix and should therefore measure conversion by lead type separately. Blending all leads into a single funnel report hides the fact that one lead type may be profitable while another is dragging down your average. Segment your funnel metrics by lead source and format, and you will quickly see where to allocate budget and where to cut.
MortgageLeads.com offers verified, real time leads across refinance, new purchase, home equity, and reverse mortgage categories, with filtering by geography and demographics and delivery options including exclusive, shared, and live transfers. Because the platform supports API integration with CRMs and quoting engines, you can route leads directly into your funnel and track stage conversion without manual data entry. That level of integration makes it easier to see exactly where purchased leads are leaking and to adjust your process accordingly. Pricing and availability change, so check current packages on the product pages before budgeting.
Metrics to Watch at Every Stage
Raw lead volume tells you almost nothing about funnel health. To manage a purchased lead funnel effectively, track a small set of stage specific metrics and review them weekly. At intake, measure lead to contact rate and average time to first contact. At first contact, measure contact rate and conversation rate. At needs analysis, measure qualification rate and average conversation length. At application, measure application start rate and application completion rate. At processing, measure approval rate, days to close, and fall through rate. At funding, measure cost per funded loan and revenue per lead. Together these metrics give you a complete picture of where leads are entering, where they are stalling, and where they are exiting without converting.
The most common mistake is to focus only on the bottom of the funnel. Lenders see a low funded loan count and assume they need more leads. In reality, a modest improvement in contact rate or application completion often produces more funded loans than a large increase in lead spend. Before you buy more leads, audit your existing funnel. Calculate contact rate, qualification rate, application rate, and close rate. Compare them to industry benchmarks and to your own historical performance. Identify the single weakest stage and fix it before moving on. This disciplined approach compounds over time and turns purchased leads from a cost center into a predictable growth engine.
Purchased leads work when the funnel around them works. Define each stage clearly, measure it honestly, and repair the leaks that matter most. Start with speed to contact, tighten your needs analysis, reduce application friction, and track fall through reasons monthly. Do that, and your mortgage sales funnel stages for purchased leads will produce the funded loans you paid for.